
Wall Street Futures Slide as Democrats Surge in Midterms, but AMD’s Blockbuster Forecast Steadies the AI Trade

United States stock futures slid on Tuesday night as early midterm election results pointed to a strong night for Democrats, while a blockbuster earnings report from chipmaker AMD offered Wall Street its most convincing evidence yet that the artificial intelligence boom still has room to run.
Contracts linked to the Nasdaq 100 fell 1.9 per cent in late evening trading in New York, according to Investor’s Business Daily, while futures on the S&P 500 dropped 1 per cent and Dow Jones futures fell 0.6 per cent. The Wall Street Journal reported a similar move, with Nasdaq 100 futures down 1.8 per cent, S&P 500 futures down 1 per cent and Dow futures down 0.6 per cent. By Wednesday morning in Asia, the selling had eased somewhat: Reuters reported that S&P 500 futures were down 0.5 per cent and Nasdaq futures down 0.9 per cent, a partial recovery from the overnight lows.
The swing captured a market caught between two powerful forces. On one side, investors were pricing in the possibility of a Democratic sweep of Congress, with all that implies for regulation of technology companies, data centres and cryptocurrency. On the other, AMD reported the largest and most profitable quarter in its history and forecast growth for 2027 far above what analysts had expected, sending its shares up about 8 per cent in extended trading and lifting the wider chip sector with it.
“For traders, the distinction between a narrow Democratic majority and a commanding victory is critical,” Chris Weston, head of research at Pepperstone, told Reuters. “A narrow blue wave may be largely priced in.” Weston added that the greatest market reaction may come not from who wins Congress, but from how decisively they win and how far the result deviates from expectations.
Futures slide as early results point to a big Democratic night
The futures market moved steadily lower through the evening as polls closed across the country and the first results came in. At 6.08pm Eastern Time, Dow futures were little changed and Nasdaq 100 futures were up 0.55 per cent, with trading still taking its cue from after-hours earnings, according to Investor’s Business Daily. By 7.48pm, after polls closed in North Carolina and Ohio, the tone had changed: Dow futures were down 0.3 per cent, S&P 500 futures down 0.3 per cent and Nasdaq 100 futures down 0.55 per cent. By 9.35pm, the losses had deepened sharply, with Nasdaq 100 futures down 1.9 per cent.
The 10-year Treasury yield fell several basis points to 4.9 per cent as investors moved towards safer assets, according to Investor’s Business Daily, after closing Tuesday’s regular session at 4.95 per cent, up six basis points on the day. Bitcoin slipped below $77,000, having traded at $77,785 at the 4pm close, while crude oil futures fell 1 per cent.
The market reaction followed a day in which Wall Street had already been braced for the vote. Democrats were favoured to capture the House of Representatives, and both parties were locked in an intense state-by-state battle for the Senate, Reuters reported. Democrats need a net gain of four seats to win control of the Senate, where 35 seats were on the ballot. Early calls went the Democrats’ way: Jon Ossoff won re-election in Georgia, marking the first significant race call of the night as polls closed in seven states, according to Reuters, while Senator Mark Warner won re-election in Virginia as expected.
Prediction markets moved even faster than the vote counts. According to Investor’s Business Daily, bettors on Polymarket put the chance of Democrats winning the Senate at 89 per cent at 6.56pm, up from roughly 75 per cent an hour earlier, and at 98 per cent by 8.34pm. Prediction markets are not results, and their odds can swing sharply on thin trading, but the direction of travel was unmistakable through the evening.
Strategists urged caution about reading too much into the overnight move. “The election results could trigger an immediate market reaction, particularly as the Senate outcome becomes clearer. However, the market’s knee-jerk trade could reverse as investors recognize that gridlock remains the most likely policy outcome in either case,” Brian Gardner, chief Washington policy strategist for Stifel, wrote in a report on Tuesday, according to Barron’s. Ryan Detrick, chief market strategist at Carson Group, warned that a decisive sweep by either party could unsettle stocks, while JPMorgan estimated that a Democratic sweep of Congress would push the S&P 500 down about 0.5 per cent on Wednesday, according to Stocktwits.
AMD’s answer: a record quarter and a 2027 forecast that stunned Wall Street
If the election was the night’s source of anxiety, AMD was its source of relief. The chipmaker reported third-quarter revenue of $13.38 billion after the market closed on Tuesday, up 45 per cent from a year earlier and ahead of the $13.09 billion analysts had expected, according to LSEG data cited by Reuters. Adjusted profit came in at $2.09 per share, against estimates of $1.95, an increase of 74 per cent from a year earlier.
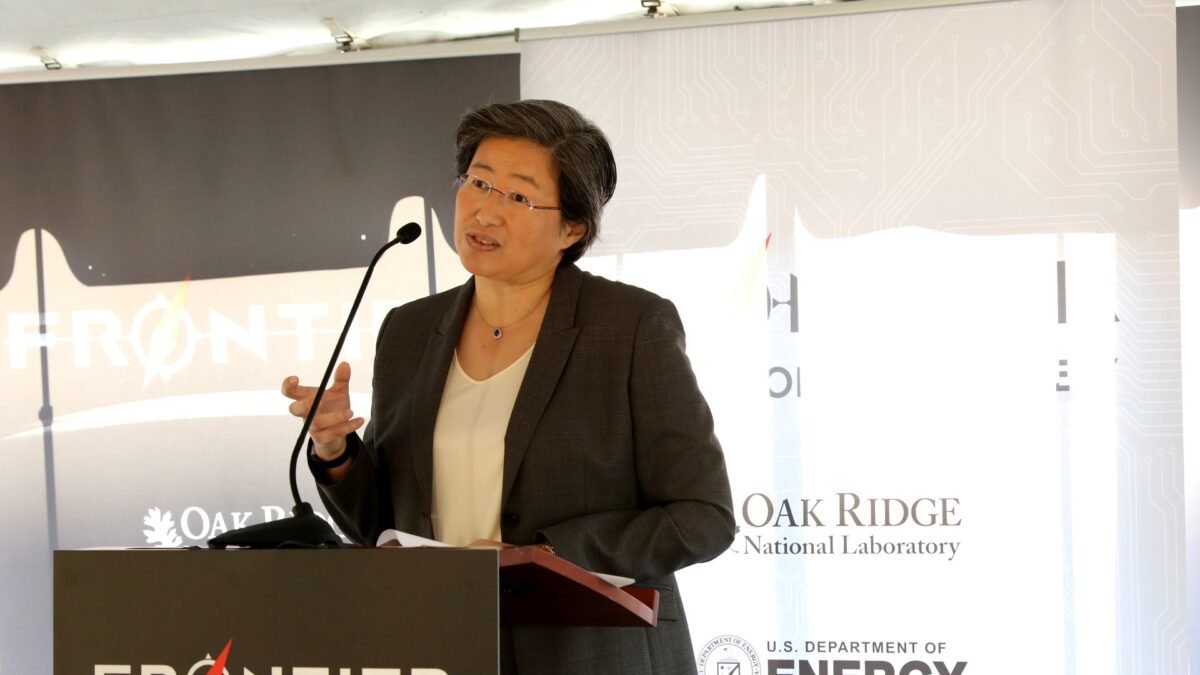
The engine of the result was AMD’s data-centre business, which brought in a record $8.55 billion, up 97 per cent year on year and ahead of estimates of about $8.20 billion, according to Reuters. Data centres supplied 64 per cent of AMD’s total revenue, up from 47 per cent a year earlier, according to CNBC. On the earnings call, chief executive Lisa Su said server revenue more than doubled in the quarter and that the company had significantly exceeded its previous outlook of more than 80 per cent growth as it gained revenue share.
It was the outlook, however, that moved the market. AMD expects fourth-quarter revenue of about $17 billion, plus or minus 3 per cent, above the average analyst estimate of $16.23 billion, according to LSEG data cited by Reuters. Looking further ahead, Su told analysts that the company expects overall revenue to rise more than 80 per cent in 2027, above the 77 per cent growth analysts had estimated. She said server revenue would double year over year in 2027, that data-centre AI revenue would grow even faster than AMD had projected 90 days earlier, and that data centres would account for more than 80 per cent of total revenue next year.
“The third quarter was the largest and most profitable in our history as we began ramping our next-generation data center products,” Su said on the call, according to the transcript published by MarketBeat. “Revenue increased 45 per cent year-over-year to $13.4 billion, driven by record EPYC and Instinct sales and strong embedded growth.”
AMD’s shares rose about 8 per cent in extended trading, according to Reuters, with CNBC putting the gain at 8 per cent. The rally spread across the chip sector: Intel’s shares rose 2 per cent, Nvidia climbed more than 1 per cent and Broadcom advanced 1.2 per cent in extended trading, according to Reuters. Arista Networks surged more than 10 per cent overnight on its own earnings beat, while Super Micro Computer also rose, according to Investor’s Business Daily. Astera Labs wavered in volatile trading and Amgen declined slightly.
Not every part of AMD’s report was strong. Sales in the client and gaming segment, home to its PC chips and console processors, fell 8 per cent to $3.72 billion, missing estimates of $3.79 billion, according to Reuters. Gaming revenue was $773 million, down 40 per cent year on year, although above the $655 million analysts had expected, according to Yahoo Finance. The weakness in consumer-facing businesses was, however, dwarfed by the data-centre surge, and the market’s verdict was unambiguous.
The wider market: Tuesday’s mixed session
The regular trading session on Tuesday had already told the story of a market torn between relief and fear. The S&P 500 rose 0.36 per cent to 7,568.92 and the Nasdaq Composite climbed 0.83 per cent to 25,372.01, snapping three-day losing streaks, while the Dow Jones Industrial Average fell 197.26 points, or 0.38 per cent, to 51,786.72, according to the Wall Street Journal. Investopedia reported the same moves: the S&P 500 and Nasdaq added 0.4 per cent and 0.8 per cent respectively, while the Dow slipped 0.4 per cent.
Chip stocks led the rebound from big recent losses ahead of AMD’s results. Nvidia rose 2.3 per cent, back above its 200-day moving average, and Microsoft climbed 2.7 per cent, back above its 50-day line, according to Investor’s Business Daily. CoreWeave jumped 7.2 per cent after hitting a record low on Monday. But the recovery regained only a portion of the recent damage: the Nasdaq had tumbled on Monday, and all the major indexes remained below their 50-day lines.
Apple and Palantir were the session’s notable fallers. Apple fell about 2 per cent after reporting better-than-expected quarterly numbers on Monday night but pointing to weakening margins, according to Investopedia. The iPhone maker reported revenue of $114.48 billion and earnings per share of $2.10, but guided December-quarter gross margin to 45 to 46 per cent, below the 46.3 per cent analysts expected, citing rising memory costs. Palantir fell more than 6 per cent on Monday after beating expectations but disappointing on the pace of contract bookings, and remained under pressure on Tuesday.
The backdrop to the week is a market still nursing the wounds of October. The Nasdaq fell about 7 per cent in October, its worst month since April 2025, and the Nasdaq 100 lost more than $2.5 trillion in value. On Monday, the Nasdaq 100 closed 1.39 per cent lower, more than 10 per cent below its 6 October all-time closing high, confirming a technical correction. Chip stocks had fallen 12 per cent over three sessions, with AMD down 7.5 per cent, Intel down 8.8 per cent and Micron down 5.8 per cent on Monday alone.
Why investors are nervous about a Democratic Congress
The market’s election-night nerves are not about the result in the abstract. They are about specific policies that a Democratic Congress could pursue, and about the sectors most exposed to them. Artificial intelligence stocks sit at the top of that list.
Many Wall Street strategists have argued that a big night for Democrats would be bad for AI stocks, according to Investor’s Business Daily. Gubernatorial races in Georgia, Ohio, Nevada and especially Texas matter because Democratic candidates in some of those races have called for an outright moratorium on data-centre development. A huge share of proposed United States data-centre projects are in Texas, where the Democratic candidate for governor, Gina Hinojosa, built an early lead in the vote count and has argued for significantly greater curbs on data-centre construction than the incumbent, Greg Abbott, has imposed. NBC projected that the Democratic candidate would take the governor’s mansion in Georgia, another big state for data-centre projects.
Ten states also have local ballot measures on data-centre construction, notably in Ohio and Maine, according to Investor’s Business Daily. The concern for investors is straightforward: data centres are the physical foundation of the AI boom, and any restriction on where they can be built, how much power they can draw or how quickly they can be approved would slow the capital spending that has driven the sector’s growth. CoreWeave, a cloud-computing company closely tied to AI infrastructure, was indicated down 4 per cent in overnight trading, according to Investor’s Business Daily, while SpaceX and Tesla sank 3 per cent on the Robinhood trading platform.
Cryptocurrency is another exposed sector. Bitcoin fell modestly below $77,000 on Tuesday night, while Robinhood and Coinbase were indicated down more than 2 per cent, according to Investor’s Business Daily. With Democrats on track to win back Congress, the outlook for sweeping crypto legislation may dim: the Clarity Act, which would set a regulatory framework for digital assets, already failed to clear Senate hurdles during the summer, and a Democratic Congress would demand an even greater role in shaping any future version.
Elon Musk’s companies face a distinct set of risks. Musk was easily the top contributor to Republican election campaigns, and a Democratic Congress could target him with hearings or investigations into his role at the Department of Government Efficiency, recent limits on Starlink and Starshield services for Ukraine, and more, according to Investor’s Business Daily. President Donald Trump has signalled that he could pre-emptively pardon Musk. It is not clear that congressional investigations would have any direct impact on SpaceX or Tesla while Trump remains in office, but heightened political opposition could affect regulatory approval for a likely merger of the two companies.
Healthcare is the counterweight. Democrats want a return of expired Biden-era enhanced Affordable Care Act subsidies and a rollback of some of the Medicaid cuts in Trump’s tax and spending law. The former would be good news for health insurers heavily exposed to the Affordable Care Act exchanges, such as Centene and Oscar Health, while the latter would boost hospital operators such as Tenet Healthcare, according to Investor’s Business Daily. But even with control of Congress, Democrats would have to reach a deal with Trump to deliver either change.
Oil, gold and Asia: the rest of the picture
Beyond equities, the night’s other markets told their own stories. United States crude oil fell 0.4 per cent to $96.09 a barrel on Tuesday, according to the Wall Street Journal, after diving 7.4 per cent on Monday. Brent crude, the international benchmark, was down 1.1 per cent at $103.60 a barrel on Tuesday, following a 7 per cent fall on Monday, according to a Hong Kong market briefing. Prices have slid to four-week lows as investors weigh hopes of a diplomatic settlement to the eight-month war between the United States and Iran against worries that recent attacks could further disrupt supplies, Reuters reported.
The effective blockade of the Strait of Hormuz, which previously carried about 20 per cent of global oil supplies, has redrawn energy flows, stoked inflation worries and upended the outlook for interest rates, according to Reuters. Three more merchant ships were struck this week, taking the total since the war began to 14, and the United States destroyed 16 Iranian mine-laying vessels on Tuesday, according to the Associated Press. Mediators from Qatar, Turkey and Pakistan are working to keep talks alive, and a draft deal has been circulating since the weekend.
In Asia, markets inched higher on Wednesday as beaten-down technology stocks found favour after AMD’s strong results eased concerns about the durability of the AI trade, Reuters reported. MSCI’s broadest index of Asia-Pacific shares outside Japan advanced 0.4 per cent, led by South Korean stocks, which rose more than 2 per cent in early trading. Japan’s Nikkei slid 1.5 per cent after returning from a holiday.
Gold, the traditional haven, rose 1.85 per cent on Monday to $3,969.60 an ounce, recovering from a one-year low, as investors sought safety from the equity sell-off. The yield on the 10-year Treasury note rose 0.058 percentage point to 4.951 per cent on Tuesday, its largest gain since 28 September, according to the Wall Street Journal, while the yield on the policy-sensitive two-year Treasury rose to 4.612 per cent. Traders are pricing in roughly a 74 per cent chance of a Federal Reserve rate rise in December.
The United States federal government shutdown reached its 34th day on Tuesday, one day short of the record 35-day shutdown in 2019, with a Senate vote on funding scheduled for Wednesday. A federal appeals court has upheld an order for full payment of November food assistance benefits, but the administration has maintained partial payments, providing only 65 per cent of maximum benefits, citing available reserves of $4.65 billion.
Analysis: Why It Matters
AMD has changed the argument about the AI trade
For weeks, the debate about artificial intelligence spending has been conducted in the abstract: are hyperscalers spending too much, too fast, on too little return? AMD’s results moved that debate onto firmer ground. A 97 per cent jump in data-centre revenue to a record $8.55 billion is not a forecast or a promise; it is cash coming through the door, from customers buying chips to run real workloads. When Lisa Su says data-centre AI revenue will grow even faster in 2027 than AMD projected 90 days ago, she is describing orders and commitments, not aspirations. That matters because the fear haunting the market since October has been that the AI boom is a bubble built on circular spending, with chipmakers selling to cloud companies that are themselves borrowing to buy. AMD’s numbers do not settle that argument, but they are the strongest evidence yet that demand for AI computing is real, broad and still accelerating.
The election result and the AI trade are now the same story
What Tuesday night made plain is that politics and technology investing can no longer be treated as separate subjects. The futures market did not fall because traders suddenly doubted AMD’s chips; it fell because the same traders who cheered AMD’s earnings also fear that a Democratic Congress will slow the data-centre build-out on which those earnings depend. Texas alone hosts a huge share of proposed United States data-centre projects, and the prospect of a governor who has campaigned for a moratorium on new construction is a direct threat to the industry’s growth plans. The irony is sharp: the strongest quarter in AMD’s history arrived on the same night that the political conditions for its customers’ expansion came under question. Investors will spend the coming weeks trying to work out which force is stronger.
A narrow win and a sweep are very different outcomes for markets
Chris Weston’s observation to Reuters deserves attention: a narrow Democratic majority may already be largely priced in, while a commanding victory is not. The market had spent weeks preparing for a Democratic House and a contested Senate. What it had not prepared for was the scale of the Democratic performance suggested by the early results, including a possible Senate majority and a string of governorships in states that matter to the AI economy. The distinction matters because a narrow majority constrains what a party can do, while a sweeping one invites ambition. Gridlock, the outcome Stifel’s Brian Gardner expects, is historically good for equities because it limits policy change. A sweeping Democratic victory would raise the odds of real action on data-centre regulation, technology oversight, healthcare subsidies and cryptocurrency rules, and the market would have to price each of those in turn.
The correction has not ended; it has changed shape
It is tempting to read Tuesday’s Nasdaq rebound and AMD’s surge as the end of the October rout. That would be a mistake. The Nasdaq 100 remains more than 10 per cent below its early-October high, the indexes are still below their 50-day moving averages, and the losses of the past three weeks have not been recovered. What has changed is the character of the selling. Monday’s rout was indiscriminate, punishing chipmakers, software companies and hyperscalers alike. Tuesday’s session and the overnight earnings reports show a market beginning to discriminate: rewarding companies with real revenue growth and punishing those whose valuations rest on promises. Apple fell on a margin warning despite beating expectations; Palantir fell despite beating expectations; AMD rose because it beat expectations and raised its outlook by a margin that left no room for doubt. That is a healthier market, but it is not yet a rising one.
The shutdown and the Fed still matter more than the election
For all the drama of election night, the forces that will matter most to markets in the coming weeks may have nothing to do with who controls Congress. The federal government shutdown is one day short of the longest in American history, and its drag on economic data, federal workers and food assistance is accumulating. The Federal Reserve, under its new chair Kevin Warsh, is weighing a December rate rise that traders price at roughly 74 per cent. The October jobs report arrives on Friday, and the ADP employment report and the ISM services survey land on Wednesday. Barron’s made the point plainly: the most important economic news that will come from Washington in the next few months arguably has nothing to do with the winners of the midterms; it is all about interest rates. The election will shape the political weather. Rates, jobs and earnings will shape the market’s direction.
What to Watch Next
- Wednesday’s cash open: whether the overnight futures losses hold into the regular session, or whether buyers step in as they did on Tuesday, will be the first test of how seriously the market takes the election result.
- The Senate picture: control of the Senate may not be known before Wednesday’s market open, and races in Alaska, Michigan, Ohio, Texas and Maine could take days to settle, keeping political uncertainty alive through the week.
- Wednesday’s data: the ADP employment report and the ISM services survey arrive on Wednesday, with the October jobs report due on Friday, offering the first hard evidence on whether the economy is cooling.
- The government shutdown vote: the Senate is scheduled to vote on funding on Wednesday, one day short of the record 35-day shutdown, and a breakthrough would remove a significant drag on sentiment.
- Chip earnings and the AI debate: with AMD’s bar now set so high, attention turns to the rest of the sector, including Qualcomm’s results on Wednesday, and to whether hyperscalers confirm or trim their capital spending plans.
Sources
- Reuters — US stock futures dip as investors await midterm election results
- The Wall Street Journal — Stock futures are falling after strong early results for Democrats
- Investor’s Business Daily — Stock market election night: tech, AI stocks lead futures lower as AMD, Arista rise on earnings
- Reuters — AMD forecast eases AI spending fears as data-center sales surge
- Investopedia — Markets news, Nov. 3, 2026: S&P 500, Nasdaq snap 3-day losing streaks as chip stocks rally

About the Author — Abdul Mannan
Related Articles
Nasdaq 100 Enters Correction as Chip Rout Deepens and Apple Slides on Margin Warning
The Nasdaq 100 has entered a correction after closing more than 10 per cent below its record high,…
Marvell’s $115 Billion Lumentum Deal Tests Wall Street’s Faith in the AI Boom as Chip Stocks Slide
Marvell agreed to buy optical-components maker Lumentum in a $115 billion all-stock deal on Monday, but both shares…
US Strips South Africa and Rwanda of Duty-Free Trade Access in AGOA Shake-Up
Washington will suspend South Africa and Rwanda from the AGOA duty-free programme from 1 January 2027, ending 26…