
Nasdaq Plunges Into Correction as Chip Rout Wipes Out Post-Midterm Rally and Dow Drops More Than 1,000 Points

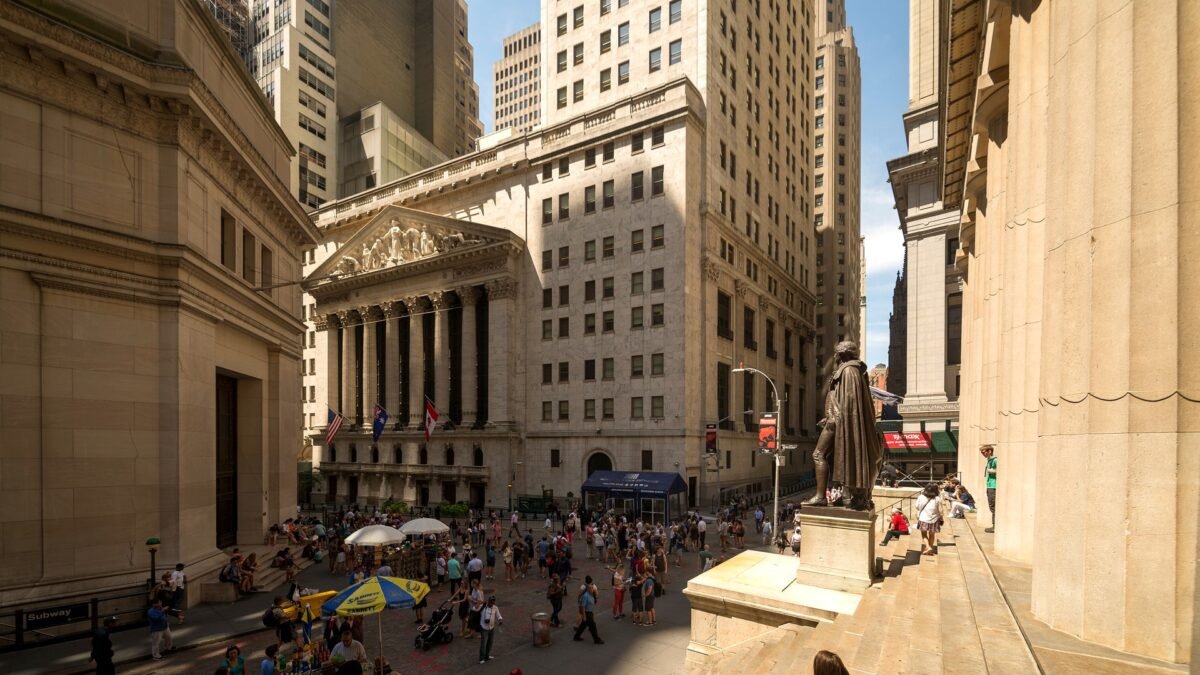
Wall Street’s post-midterm rally lasted barely a day. The Nasdaq Composite plunged into correction territory on Thursday, 5 November, as a brutal sell-off in chipmakers and artificial intelligence stocks wiped out the previous session’s gains and dragged the Dow Jones Industrial Average down by more than 1,000 points, according to Reuters and CNN.
The tech-heavy Nasdaq fell by as much as 5.7 per cent during the session, according to CNN, trading more than 10 per cent below its record closing high of 27,599.89 set on 6 October — the technical definition of a correction. By the close of trading it was on course for its worst day since April 2025, when President Donald Trump’s sweeping “Liberation Day” tariffs sent markets reeling. The narrower Nasdaq-100, which had already confirmed a correction on Monday, fell about 5.2 per cent on Thursday, a drop that Reuters said would erase more than $2 trillion in market value if the losses held.
The selling was broad and relentless. At 12:24 p.m. ET, the Dow had fallen 1,403.66 points, or 2.63 per cent, to 51,952.46, the S&P 500 had lost 262.17 points, or 3.41 per cent, to 7,426.41, and the Nasdaq Composite was down 1,173.62 points, or 4.55 per cent, to 24,564.36, according to Reuters. All 11 major S&P 500 sectors were in negative territory by midday, with technology and consumer discretionary leading the losses. Investor’s Business Daily reported in afternoon trade that the Dow was down nearly 3 per cent, or more than 1,500 points, while the Nasdaq was down 4.6 per cent and the S&P 500 had fallen 3.6 per cent.
The proximate cause of the rout was politics. Investors spent Thursday weighing whether the Democrats’ sweeping victory in Tuesday’s midterm elections — which delivered them control of both the House of Representatives and the Senate — would slow the massive buildout of data centres that has powered the AI boom, according to Reuters and CNN. Shares of semiconductor makers and the “picks and shovels” of the data-centre buildout, which had already been falling on Wednesday beneath the surface of the broader rally, collapsed on Thursday as that selling pressure intensified.
Key to the sell-off, according to CNN, is the Democrats’ victory in the Texas governor’s race. Texas has played a crucial role in accelerating AI development, with Google, Meta, Oracle and OpenAI all making massive investments in data centres there. Governor-elect Gina Hinojosa campaigned on a temporary moratorium on new data centres and on eliminating certain tax incentives for companies building them in the state. Investors are now asking whether similar restrictions could spread to other states that host planned data-centre hubs, and whether a Democratic Congress will subject the industry’s aggressive expansion to far tougher scrutiny.
“There is now a chance that the two years of extra push from the Trump government for AI buildout will somehow be scaled back because there has been a lot about the AI trade that has been ignored by the current administration,” Ipek Ozkardeskaya, a senior analyst at Swissquote Bank, told Reuters. “We suspect there is going to be some scrutiny on this aggressive AI buildout.”
The chip sector bore the brunt of the decline. The Philadelphia Semiconductor Index, a closely watched gauge of chipmakers, fell 7.1 per cent in morning trade and was down as much as 10 to 11 per cent at its session low, according to Reuters, putting it on track for its worst weekly performance since the April 2025 tariff-driven rout. Nvidia, the world’s most valuable chipmaker and the symbol of the AI trade, sank about 7 per cent on Thursday, erasing its gains for the year, according to CNN. Advanced Micro Devices fell 13 to 15 per cent, Micron Technology slid more than 12 per cent, and SanDisk plunged about 20 per cent, according to Investor’s Business Daily and Reuters.
Qualcomm dropped 9 to 11.5 per cent after the chipmaker fell short of Wall Street estimates for fourth-quarter smartphone chip sales, citing sluggish demand and declining Apple-related revenue, according to Reuters. The company also warned that higher memory chip costs were hurting sales, echoing guidance from Intel last week. CNN reported that Qualcomm was set for its worst day since March 2020. Intel and Marvell Technology also fell sharply, while Dell, the AI server maker, dropped 10.5 per cent, according to Reuters.
The pain spread well beyond the chipmakers. Data-centre operators IREN, Hut 8 and Applied Digital fell between 6 and 11 per cent, according to Reuters, while the so-called neoclouds that rent out computing power for the AI boom — CoreWeave and Nebius — plunged roughly 11 and 15 per cent respectively, according to CNN. Utilities and equipment suppliers exposed to the data-centre boom, including GE Vernova and Constellation Energy, were also trading lower. Tesla tumbled 9.5 to 11 per cent and SpaceX eased 6.7 to 9 per cent, according to Reuters and CNN, extending losses for companies led by Elon Musk, who spent nearly half a billion dollars backing Republican candidates, including efforts to keep them in control in Texas, the home state of both companies.
Meta Platforms slid 3.4 per cent, while Amazon and Alphabet were slightly lower after surging on Wednesday, according to Reuters. Snapchat owner Snap slid 12 per cent after missing third-quarter revenue estimates, while marketing platform AppLovin jumped 32 per cent after beating third-quarter profit estimates, according to Reuters. Expedia tumbled more than 13 per cent after disappointing investors with a soft outlook for holiday bookings in the current quarter, even though it reported third-quarter earnings of $9.39 per share, above views of $8.85, according to Investor’s Business Daily.
Wall Street’s fear gauge, the CBOE Volatility Index, known as the VIX, surged 50 per cent and hit its highest level in seven months, according to CNN, as investors rushed to hedge against further declines. Declining issues outnumbered advancers by a 1.36-to-1 ratio on the New York Stock Exchange and by a 2.17-to-1 ratio on the Nasdaq, according to Reuters. The Nasdaq recorded 430 new lows against 140 new highs by midday, according to Reuters.
The reversal was all the more striking because it came less than 24 hours after one of the strongest post-election rallies in decades. On Wednesday, the Dow had surged 1,569 points — its best post-midterm rally since 1982 — while the S&P 500 advanced 1.58 per cent and the Nasdaq gained 1.44 per cent, as investors initially celebrated the end of political uncertainty. Reuters noted that Wednesday’s rally was the benchmark’s biggest one-day percentage gain in three months. But even on Wednesday, the chipmakers were already falling beneath the surface, a warning sign that the rally was built on shaky foundations.
Thursday’s sell-off also rippled through other markets. West Texas Intermediate crude oil futures rose nearly 3 per cent to around $90.65 a barrel, while the 10-year Treasury yield slipped 6 basis points to 4.84 per cent as investors sought safety, according to Investor’s Business Daily. Bitcoin fell to around $76,300. Gold rose about 1 per cent to near $4,115 an ounce, according to market data cited in press reports.
Attention now turns to Friday’s US October jobs report, due at 8:30 a.m. ET, which is expected to show the economy added 62,000 jobs during the month, up from 29,000 in September, with the unemployment rate seen flat at 4.2 per cent, according to Econoday figures cited by Investor’s Business Daily. Traders currently expect the Federal Reserve to raise interest rates next month following its September rate hike, according to Reuters. Cleveland Federal Reserve President Beth Hammack said in comments on Thursday that she favoured a gradual rate-hike path to bring inflation down, according to Reuters.
The sell-off came on the same day the Bank of England raised interest rates to 4 per cent, its first increase in more than three years, as energy-driven inflation heads towards 5 per cent in Britain — a decision NEXA reported earlier on Thursday.
Analysis: Why It Matters
Thursday’s rout matters for reasons that go well beyond one bad day on Wall Street. It is the moment when the market’s two-year love affair with artificial intelligence collided, head-on, with democratic politics — and the collision exposed just how much of the AI boom was built on the assumption that nothing would ever get in its way.
The rally that lasted a day
The speed of the reversal is itself the story. On Wednesday, investors celebrated the Democrats’ victory as the end of uncertainty: the Dow’s 1,569-point surge was the strongest post-midterm rally in 44 years. By Thursday afternoon, that entire gain had been erased, and then some. Markets do not normally reverse a historic rally within 24 hours unless the rally itself was based on a misreading — and the misreading here was straightforward. Investors initially assumed that a Democratic Congress would mean gridlock, and gridlock would mean no new rules for anyone. It took less than a day for them to realise that the new Congress might have very specific plans for one industry in particular: the data-centre buildout that has consumed trillions of dollars of capital, vast amounts of electricity and water, and enormous tracts of land in communities that never asked for it.
Keith Lerner, chief investment officer at Truist Advisory Services, told CNN that he saw this week’s volatile moves as more of a knee-jerk reaction than a real indication of how stocks, particularly technology, could fare under Democratic control of Congress. He may be right about the knee-jerk element. But knee-jerk reactions do not erase $2 trillion of market value in a single session unless the underlying trade was already fragile. The Nasdaq had already entered correction territory once in March, nearly did so again in late July, and saw its narrower Nasdaq-100 index confirm a correction on Monday, 2 November — three days before Thursday’s plunge. The market was already wobbling before the election gave it a reason to fall.
The Texas question
The most important single fact behind Thursday’s sell-off may be the least financial one: a governor’s race in Texas. Governor-elect Gina Hinojosa campaigned on a temporary moratorium on new data centres and on scrapping the tax incentives that lured them to Texas in the first place. That matters because Texas is not a peripheral player in the AI buildout — it is the centre of it. Google, Meta, Oracle and OpenAI have all poured money into Texas data centres, drawn by cheap land, cheap power and a regulatory environment that, until now, has asked few questions.
What investors are really pricing in is not one moratorium in one state. It is the possibility that the political consensus which allowed the buildout to proceed at breakneck speed — with minimal scrutiny of its energy use, its water consumption, its effect on local electricity prices and its strain on power grids — is breaking down. Public opposition to the industry’s rapid expansion has been growing in several key data-centre states, according to Reuters, and the election results suggest that opposition now has political champions with real power. If Texas can slow the buildout, other states can too. And if the buildout slows, the entire chain of companies that supply it — chipmakers, server builders, power suppliers, construction firms — faces a demand shock.
This is why the selling was concentrated where it was. It was not a broad flight from equities: energy stocks actually gained on Thursday, according to Reuters. It was a targeted repricing of a single, specific bet — the bet that AI infrastructure spending would grow without limit, without friction and without political cost. That bet is now, at minimum, in doubt.
A bubble letting out air — or bursting?
Ed Yardeni, president of Yardeni Research, offered the most striking framing of the day. “We want a slowdown in the AI buildout. It was too frenzied and speculative,” he told CNN. “Now we are letting air come out of the AI bubble. It’s better to let air come out of the AI bubble than let it burst.”
Yardeni’s distinction — between air coming out and a burst — is the question that will define the next year of markets. The case for “air coming out” is that the underlying technology is real, demand for computing is genuine, and a slower, more disciplined buildout would be healthier for everyone. The case for something worse is the sheer scale of the spending: Goldman Sachs has estimated hyperscaler capital expenditure at roughly $800 billion in 2026, rising towards $1.2 trillion in 2027, much of it financed with debt. If the buildout slows while the debt remains, the mathematics turn ugly very quickly. The warning signs have been accumulating for weeks: chip stocks sliding since early November, the Nasdaq-100 entering correction on Monday, and doubts about whether the enormous sums being poured into data centres will ever generate commensurate returns.
Thursday’s selling also exposed a second vulnerability: the AI trade had become a crowded trade, and crowded trades unwind violently. When Nvidia can lose 7 per cent in a day and erase its entire gain for the year, when SanDisk can fall 20 per cent and AMD 15 per cent, the market is not calmly reassessing fundamentals — it is rushing for the exits. The VIX’s 50 per cent surge to a seven-month high tells the same story: fear, not calculation, drove much of the day.
What the earnings told us
Politics was the trigger, but earnings provided the ammunition. Qualcomm’s miss — weaker smartphone chip sales, falling Apple-related revenue, and rising memory costs squeezing margins — was a reminder that the semiconductor cycle is not immune to ordinary economics. Investors are now punishing any company that misses forecasts, however slightly. Snap fell 12 per cent on a revenue miss. Expedia fell 13 per cent despite beating earnings, because its outlook for the holiday quarter disappointed. This is a market with no tolerance left for bad news, which is itself a sign of how stretched valuations had become.
The memory-chip cost problem is worth pausing on. Qualcomm blamed higher memory prices for hurting its sales — the same dynamic Intel flagged in its guidance last week. Memory is the lifeblood of AI computing, and its price is rising precisely because AI demand is so intense. There is an irony here that the market is only beginning to digest: the AI boom is making the components of AI more expensive, which squeezes the margins of the companies building it, which makes investors question the boom. It is a feedback loop, and on Thursday it ran in the wrong direction.
The rest of the world is watching
Thursday’s rout was an American event with global consequences. European markets, which had rallied on Wednesday, gave up their gains on Thursday as the Wall Street sell-off gathered pace; London’s FTSE 100, which had hit an intraday record high of 10,948.24 in the morning, closed down 0.4 per cent at 10,782.66, according to Sharecast. The Bank of England’s rate hike to 4 per cent — its first in more than three years — added to the sense of a world in which money is getting more expensive just as the most expensive bet in market history is being questioned.
For ordinary investors, the lesson of Thursday is not that AI is finished. The technology is real, the demand is real, and the companies at the centre of it remain enormously profitable. The lesson is that the market had priced in a future in which nothing went wrong — no regulation, no local opposition, no earnings misses, no political change. That future ended on Tuesday night. What replaces it will be messier, slower and more contested. Whether that is a healthy correction or the beginning of something worse will depend on what happens next: Friday’s jobs report, the Federal Reserve’s December decision, and, above all, what the new Congress actually does when it takes its seats in January.
What to Watch Next
- Friday’s jobs report: The US October non-farm payrolls report, due at 8:30 a.m. ET on Friday, is expected to show 62,000 new jobs and unemployment steady at 4.2 per cent. A weak number could deepen the sell-off; a strong one could steady nerves — and shape the Federal Reserve’s December rate decision.
- The Federal Reserve’s December meeting: Traders currently expect the Fed to raise rates next month, according to Reuters. Any signal from Fed officials in the coming days about whether the market turmoil changes that calculation will be watched closely.
- What Democrats actually propose on data centres: Campaign promises are one thing; legislation is another. Watch for the first concrete proposals on data-centre regulation, tax incentives and energy use from the incoming Congress — and from Governor-elect Hinojosa in Texas.
- Nvidia and the chipmakers’ next results: With Nvidia’s shares having erased their 2026 gains, the next round of chipmaker earnings will be a critical test of whether demand for AI hardware is holding up or cracking under the weight of its own costs.
- Whether the selling spreads: Thursday’s losses were concentrated in technology and AI-linked stocks, with energy gaining. If the rout broadens into banks, consumer stocks and the wider market, it would signal a much deeper loss of confidence.
Sources
- Reuters via Kitco — “Wall St slumps as sharp tech losses put Nasdaq on course for correction” (5 November 2026)
- CNN — “Stocks plunge as midterm results send AI trade into a tailspin” (5 November 2026)
- Investor’s Business Daily — “Stock Market Today: Dow Down 1,500 Points As Volatility Spikes” (5 November 2026)
- New York Post — “Nasdaq plunges into correction territory as Dem wins threaten data centers” (5 November 2026)
- Reuters via SRN News — “Nasdaq set to confirm correction as AI stocks tumble” (5 November 2026)
- Reuters — “S&P 500 futures steady after midterm rally; Nasdaq lags on chip weakness” (5 November 2026)

About the Author — Abdul Mannan
Related Articles
China Blocks SoftBank’s $5.4 Billion Takeover of ABB’s Robotics Unit in Blow to Son’s Physical AI Ambitions
China has told SoftBank it will not allow its $5.4 billion purchase of ABB's robotics division, ABB confirmed…
Dow Soars 1,569 Points in Best Post-Midterm Rally Since 1982 as Democrats’ Sweep Sends Oil Plunging
Wall Street staged its biggest post-midterm rally since 1982 as the Dow surged 1,569 points and Brent crude…
Euro Zone Inflation Hits Three-Year High of 4% as Energy Costs Surge, Putting December ECB Rate Rise in Sight
Euro area inflation rose to 4.0 per cent in October, its highest in three years, as energy prices…