
Reliance Posts Record Quarterly Profit as Refining Windfall and Jio Listing Cap a Historic Week

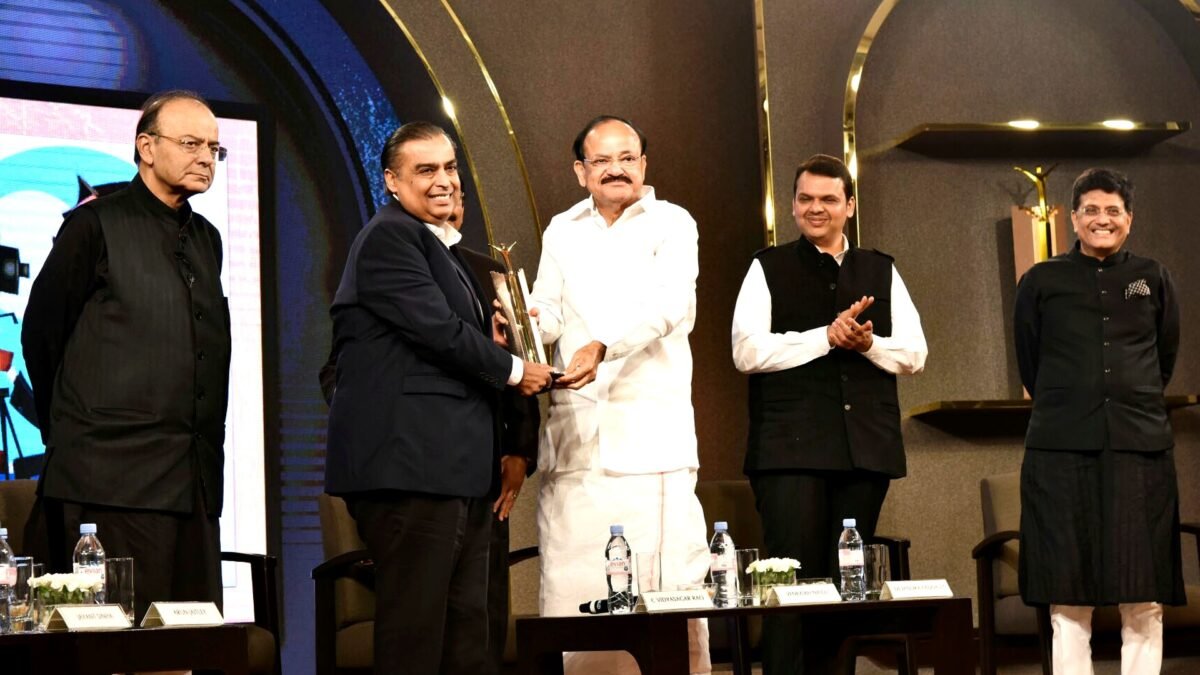
Reliance Industries, India’s largest company by market value, has reported the biggest quarterly profit in its history, capping a week in which its telecoms arm, Jio Platforms, completed India’s largest-ever stock market listing. The results, announced after Indian markets closed on Friday, will face their first test from investors when trading resumes on Monday, 2 November.
Consolidated profit after tax, including the share of associates and joint ventures, rose 33.8 per cent from a year earlier to Rs 29,550 crore (about $3.1 billion) in the three months to 30 September, the second quarter of Reliance’s financial year, according to the company’s filing with the stock exchanges. Profit attributable to Reliance shareholders climbed 40.6 per cent to Rs 25,548 crore (about $2.7 billion), from Rs 18,165 crore a year earlier, comfortably beating the average analyst estimate of Rs 21,419 crore cited by Reuters.
Gross revenue rose 27.8 per cent to a record Rs 3,62,268 crore (about $38.1 billion), while revenue from operations increased 28.5 per cent to Rs 3,32,861 crore. Earnings before interest, tax, depreciation and amortisation (EBITDA) climbed 23.9 per cent to a record Rs 62,409 crore, although the consolidated EBITDA margin narrowed by 60 basis points to 17.2 per cent. For the first half of the financial year, consolidated profit reached Rs 52,746 crore, up 20 per cent, crossing the Rs 50,000 crore mark in a single half-year for the first time on a recurring basis.
The headline numbers were driven overwhelmingly by the oil-to-chemicals business, which runs the world’s largest single-site refining complex at Jamnagar in Gujarat. Its EBITDA jumped 67.9 per cent to a record Rs 25,203 crore, on revenue that surged 44.2 per cent to Rs 2,31,601 crore. Crude prices for the quarter rose 40.6 per cent year on year, while transportation fuel prices climbed between 50 and 78 per cent, widening the refining margins on which Reliance’s core business depends.
The digital services business provided the second engine of growth. Jio Platforms, India’s largest mobile carrier, reported its first quarterly results as a separately listed company, with profit after tax up 13.7 per cent to Rs 8,387 crore and revenue up 11.4 per cent to Rs 40,475 crore. Digital services revenue rose 11.3 per cent to Rs 47,485 crore, and EBITDA increased 16.6 per cent to Rs 21,879 crore, with the margin widening by 250 basis points to 54.1 per cent.
Jio added 9.1 million subscribers during the quarter, taking its total base to 542 million, and crossed two milestones: 300 million 5G mobile subscribers and 30 million fixed broadband subscribers. Average revenue per user rose to Rs 218.8. The profit growth was held back by higher finance costs after 5G network assets were moved onto Jio’s books in March.
The results came three days after Jio Platforms completed a Rs 30,188 crore initial public offering on 28 October, described by the company as India’s largest IPO to date. The shares listed at a 26.7 per cent premium to the issue price, giving the company a market value of about Rs 13.1 lakh crore (about $137 billion) and making it India’s second-most valuable listed company, behind only its parent. The offering was subscribed more than 22 times.
“This week marked a historic moment in Reliance’s value creation journey with Jio’s record-setting listing on Indian bourses,” chairman and managing director Mukesh Ambani said in a statement accompanying the results.
Not every part of the sprawling group shared in the record. Reliance Retail, India’s largest retailer, was the weak spot: its core earnings fell 10.2 per cent and its margin narrowed by 120 basis points to 7.8 per cent, with profit down 24.3 per cent to Rs 2,611 crore. Reuters reported that digital-commerce spending, higher input costs and the later timing of the Diwali festival contributed to the pressure. Earnings from the oil and gas exploration business also declined.
Reliance’s board also passed an enabling resolution authorising the issue of non-convertible debentures of up to Rs 15,000 crore in one or more tranches on a private placement basis. Net debt stood at Rs 1,17,140 crore at the end of September, down from Rs 1,22,914 crore at the end of the preceding quarter.
The company filed a transcript on 1 November of its analyst meeting held on 30 October, in which group chief financial officer V. Srikanth said first-half performance was tracking an annualised consolidated EBITDA of more than Rs 80,000 crore — a company-stated trajectory, not an audited forecast. The meeting also heard that earnings from the new energy business are expected to begin contributing in the 2027-28 financial year.
Reliance shares closed at Rs 1,164.90 on Friday, 30 October, and have had a difficult year despite the earnings increase, Reuters reported, trading well below their 200-day average. Monday’s session will offer the first indication of how investors weigh a record quarter against the questions hanging over the group’s next phase.
The refining windfall behind the record
The oil-to-chemicals division delivered the best quarterly performance in its history, and the reasons lie largely outside Reliance’s control. Global fuel markets have been tight and volatile through 2026, with crude prices elevated by the war in the Middle East and by disruptions to shipping through the Strait of Hormuz. Brent crude, the international benchmark, settled above $113 a barrel on Friday and gained 13.6 per cent across October, its fourth consecutive monthly rise.
When crude prices rise sharply, refiners that can buy a wide range of crude grades and turn them into high-value fuels tend to prosper, provided the price of refined products rises faster than the cost of the crude going in. That is what happened in the September quarter: transportation fuel prices rose by 50 to 78 per cent year on year, far outpacing the 40.6 per cent rise in crude, and Reliance’s Jamnagar complex — with its ability to process cheaper, heavier crudes that many rivals cannot handle — was positioned to capture the widest margins.
The scale of the gain is visible in the segment’s numbers. Oil-to-chemicals revenue of Rs 2,31,601 crore was up 44.2 per cent, and EBITDA of Rs 25,203 crore was up 67.9 per cent, accounting for roughly two-fifths of the group’s entire operating profit. A year earlier the same business earned Rs 15,008 crore. The swing of more than Rs 10,000 crore in a single segment explains most of the group’s record quarter.
The same forces lifted other Indian energy companies. Indian Oil Corporation, Bharat Petroleum and Hindustan Petroleum reported a combined standalone net profit of Rs 30,106 crore for the September quarter, rebounding from losses in the previous quarter on refining margin gains. The pattern confirms that the September quarter was an industry-wide windfall, not a Reliance-specific one — and that is precisely why investors will be cautious about extrapolating it.
Jio’s listing changes the shape of the group
If refining supplied the profit, Jio supplied the story. The listing of Jio Platforms on 28 October was the largest IPO in Indian history, raising Rs 30,188 crore, and it formally turned India’s biggest telecoms operator into a separately valued public company. At its listing-day market value of about Rs 13.1 lakh crore, Jio became the second-most valuable listed company in India, behind only Reliance itself.
The listing matters for two reasons. First, it gives investors a direct way to value the digital business, which has long been buried inside a conglomerate dominated by refining. For years, analysts have argued that Reliance trades at a discount because the market cannot easily separate a fast-growing telecoms and digital business from a cyclical refining one. A separately listed Jio, with its own share price, quarterly results and investor base, makes that separation visible — and makes the parent’s remaining businesses easier to judge on their own merits.
Second, the IPO proceeds were used largely to prepay borrowings, strengthening a balance sheet that has carried heavy debt from the 5G rollout. Jio’s profit growth of 13.7 per cent was held back by higher finance costs after 5G network assets were capitalised in March, so reducing debt directly supports the earnings trajectory the market will now scrutinise quarter by quarter.
The operating numbers justify the attention. A subscriber base of 542 million, with 300 million on 5G and 30 million fixed broadband connections, gives Jio a scale no rival in India can match. Average revenue per user of Rs 218.8 is rising, and the digital services EBITDA margin of 54.1 per cent — up 250 basis points — shows the operating leverage of a network built at enormous upfront cost now being monetised. The question for the coming quarters is whether Jio can keep raising prices and adding higher-value subscribers without losing the mass-market customers who made it dominant.
Retail’s stumble and the consumer test
The one clear disappointment in the quarter was retail. Reliance Retail’s core earnings fell 10.2 per cent, its margin narrowed to 7.8 per cent, and profit dropped 24.3 per cent to Rs 2,611 crore. The company and analysts cited a mix of causes: spending on digital commerce, higher input costs, and the later timing of Diwali, which pushed some festive-season sales into the current quarter.
The explanation is plausible, but it will need proving. Retail is the part of Reliance most exposed to the Indian consumer, and it is the business the group has spent the most money building over the past decade. If the weakness is genuinely a matter of timing, the December quarter — which captures the full festive season — should show a sharp recovery. If it does not, investors will start asking whether competition from quick-commerce platforms and the cost of the digital build-out are doing lasting damage to margins.
The broader Indian consumer picture is mixed. Maruti Suzuki, the country’s largest carmaker, reported its highest-ever monthly sales in October on festive demand, and Hyundai Motor India also set a monthly record, suggesting consumers are spending. But that spending is concentrated in big-ticket items and festive purchases; the everyday retail environment remains competitive and price-sensitive. Reliance Retail’s next quarter will be read as a verdict on which of those two pictures is closer to the truth.
A record built on borrowed tailwinds
There is an irony at the heart of Reliance’s record quarter: the same geopolitical crisis that has unsettled global markets has enriched its refining business. The war in the Middle East, now in its ninth month, has pushed crude prices higher, widened fuel margins and disrupted the shipping lanes on which the oil trade depends. Reliance, sitting on the world’s largest refining complex and able to process a wide range of crudes, has been one of the commercial beneficiaries.
That makes the record fragile in a specific way. A ceasefire, a normalisation of shipping through the Strait of Hormuz, or a fall in crude prices would narrow the very margins that produced the Rs 25,203 crore oil-to-chemicals result. The company knows this: its own commentary has consistently framed the refining business as cyclical, and its long-term strategy — the new energy business, whose earnings are expected to begin in 2027-28 — is explicitly designed to reduce dependence on fossil-fuel margins over time.
For now, though, the refining windfall is funding everything else: the 5G network, the retail expansion, the consumer goods push and the new energy build-out. The record profit is, in that sense, both a result and a resource — the cash engine that pays for the transformation of the group.
Analysis: Why It Matters
1. The refining windfall is real, but it is borrowed from war
Reliance’s record quarter rests on margins created by conflict. Crude up 40.6 per cent and fuel prices up as much as 78 per cent is not a normal market; it is a market distorted by war, sanctions and shipping disruption. The company earned its windfall honestly — its refining configuration genuinely captures more of the margin than rivals can — but investors should not mistake a war premium for a permanent improvement. The honest test of the result is not whether Reliance can repeat Rs 29,550 crore next quarter, but whether the underlying businesses are stronger when the premium fades. On that test, the Jio numbers matter more than the refining ones.
2. Jio is now the growth story investors actually price
Before the listing, Jio was a division inside a conglomerate; now it is a separately traded company with a market value of about Rs 13.1 lakh crore. That changes the conversation around Reliance entirely. The parent can no longer be judged as a single opaque entity: the market will price Jio on subscriber growth, pricing power and margins, and price the rest of Reliance on refining, retail and energy. If Jio keeps growing — 300 million 5G users and a 54.1 per cent EBITDA margin suggest it can — the conglomerate discount that has weighed on Reliance for years may finally begin to close. If Jio disappoints, there will be nowhere to hide.
3. Retail’s stumble tests the consumer bet
Reliance has spent a decade and vast sums building the retail business into India’s largest. A 24.3 per cent fall in profit, even with a plausible explanation in Diwali timing, is a warning sign in a business where scale is supposed to protect margins. The December quarter is now a credibility test: festive-season sales should deliver a strong recovery, and if they do not, the market will conclude that the problem is structural — competition, costs or both — rather than seasonal. The retail division is where Reliance’s consumer ambitions meet their hardest examination.
4. The market’s verdict on Monday matters more than the numbers
Reliance shares have had a difficult year, trading well below their 200-day average even before these results. That tells its own story: the market had already discounted a strong quarter, or doubted that the strength would last. Monday’s trading will show whether investors see the record as a turning point or as the peak of a cycle. A strong rally would signal belief in the Jio story and in the durability of the new structure; a muted reaction would signal that the market views the refining windfall as transient and is waiting for proof from retail and new energy. The share price, in short, is the market’s review of the strategy, not just of the quarter.
5. India’s earnings season is telling a two-speed story
Reliance’s results sit inside a broader Indian corporate earnings season that is splitting in two. Energy and telecoms are booming on the back of global prices and domestic scale, while consumer-facing businesses are fighting for margin. The oil refiners’ combined Rs 30,106 crore profit and the record festive auto sales point in the same direction: capital-intensive, scale-driven businesses are thriving, while businesses that depend on everyday consumer spending are under pressure. That divide is the real economic story of India in late 2026, and Reliance — which straddles both sides — is its clearest single example.
What to Watch Next
- Monday’s market reaction: How Reliance and Jio Platforms shares trade on 2 November, the first session after the results, will show whether investors treat the record as a turning point or a cyclical peak.
- Jio’s December-quarter pricing: Whether average revenue per user keeps rising and 5G additions continue will determine if the newly listed company justifies its Rs 13.1 lakh crore valuation.
- Retail’s festive-season recovery: The December quarter should show whether the September weakness was Diwali timing or something structural in Reliance Retail.
- Oil prices and the Middle East: Any ceasefire or normalisation of shipping through the Strait of Hormuz would narrow the refining margins behind the record quarter.
- New energy’s first earnings: The company says earnings from its new energy business should begin in 2027-28; the scale and timing of that contribution will shape the next phase of Reliance’s transformation.
Sources
- Reliance Industries posts highest-ever Q2 revenue, profit surges 33.8% — TradingView / Moody’s
- Reliance Posts Record Quarterly Profit As Oil-To-Chemicals Windfall, Jio Listing Power Q2 — Outlook Business
- Reliance Q2 results: Net profit jumps 41% YoY to ₹25,548 crore — Upstox
- RIL, JPL Q2 results: shares in focus on Monday 2 Nov — TradingView / Moody’s
- Reliance Industries Q2 FY27 Analyst Meet Key Highlights — Kalkine

About the Author — advmannan1
Related Articles
Qatar Shares Surge 4.6% as Gulf Markets Slide on Fears of Renewed US–Iran Conflict
Qatar's stock market posted its sharpest gain in more than eight years on Sunday, defying a regional slide…
South Korea’s Exports Nearly Double in October as AI Chip Boom Puts $1 Trillion Year Within Reach
South Korea's exports jumped 93.7% to $115.28 billion in October — the sharpest rise since 1974 — as…
Binance Says 90% of $6.3 Billion Stolen in Record Hack Is Covered as FBI Blames North Korea
Binance says it has covered 90 per cent of the $6.3 billion stolen in the largest crypto theft…