
Global Stocks Roar Back as CoreWeave Revives the AI Trade and Europe Hits a Record High

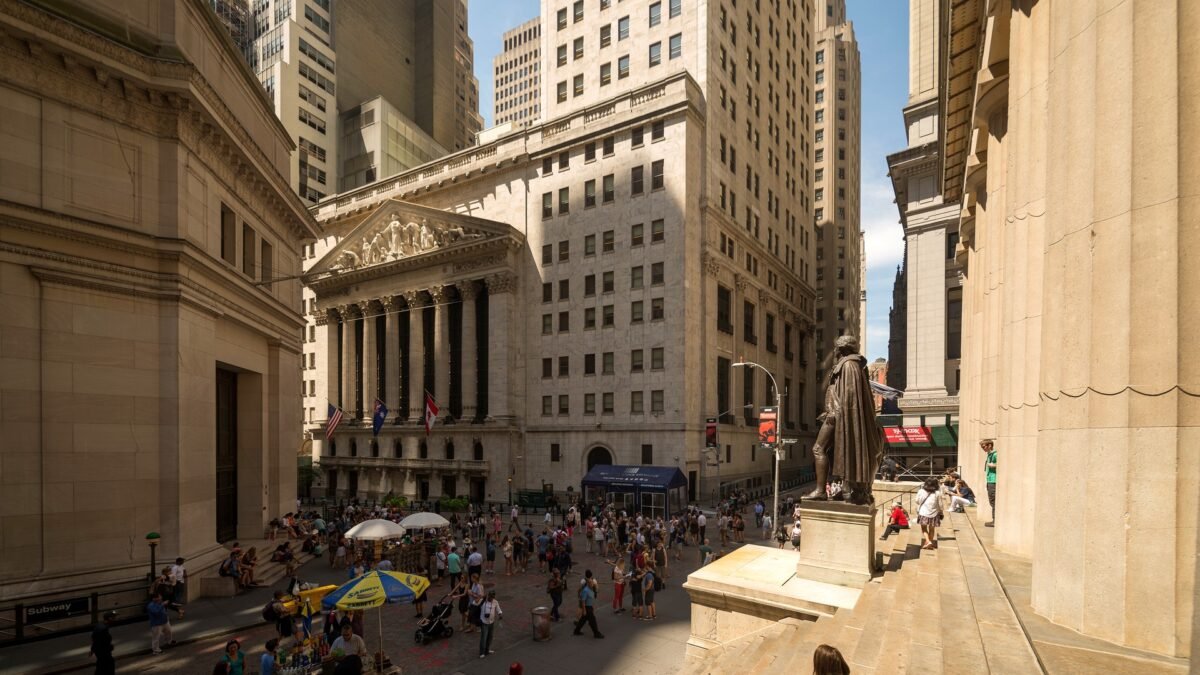
Global stock markets roared back on Wednesday, 11 November, as a strong set of results from artificial intelligence infrastructure firm CoreWeave revived confidence in the technology trade and lifted shares on both sides of the Atlantic, according to Reuters. The rebound came just a day after hot American inflation data and hawkish talk from Federal Reserve officials had sent Wall Street lower and pushed bets on a December interest rate rise sharply higher.
The Nasdaq Composite climbed 1.6 per cent, the S&P 500 rose 1.3 per cent and the Dow Jones Industrial Average added 0.5 per cent, according to Reuters. In Europe, the pan-European STOXX 600 index closed at a record high of 663.05 points, up 0.7 per cent on the day, while London’s FTSE 100 gained 0.8 per cent. Japan’s Nikkei rose 1.3 per cent and Chinese shares added 0.4 per cent, as Asian markets extended a recovery that has now run for three consecutive sessions.
The rally was broad. According to Reuters, all eleven sectors of the S&P 500 rose on Wednesday with the sole exception of consumer discretionary stocks. Technology shares gained 2.7 per cent and energy stocks rose 1.8 per cent, while semiconductor shares surged 5.6 per cent. The scale of the turnaround was striking because it arrived against a backdrop that, on paper, should have frightened equity investors: American interest rates are now expected to rise again in December, the dollar is at its strongest level in nineteen months, and the yield on the benchmark ten-year Treasury note is hovering close to five per cent.
What changed the mood was one company. CoreWeave, a cloud computing business that rents out the specialised computing power used to train and run large artificial intelligence models, reported third-quarter revenue of 3.66 billion dollars, up from 1.37 billion dollars a year earlier, an increase of about 168 per cent. It also raised its revenue forecast for 2026 to between 13.0 billion and 13.3 billion dollars and told investors it expected to become profitable in 2028. Its shares surged about 20 per cent on Wednesday, according to Reuters, after rising 16 per cent in premarket trading. MarketWatch put the intraday gain at nearly 25 per cent.
The result mattered far beyond one stock because CoreWeave had become, in the space of a few weeks, the market’s shorthand for the doubts gathering around the artificial intelligence boom. Its shares had fallen to an eighteen-month low the previous week after a Democratic sweep in the United States midterm elections triggered a sharp sell-off in artificial intelligence-related stocks, on concerns that infrastructure investment could slow. Investors had begun to ask whether demand for computing power was strong enough to support the enormous debt-funded expansion under way across the sector. CoreWeave’s answer, delivered in its results and on its earnings call, was that demand remained very strong, and the market believed it, at least for a day.
CoreWeave calms the market’s worst fear
“The results confirm that demand for AI is still very strong,” Alberto Conca, the chief investment officer at Swiss wealth manager LFG+ZEST, told Reuters. But he added a caution that ran through much of the day’s commentary: “However, CoreWeave still faces significant questions over the sustainability of its debt burden.”
That caution is well founded. Alongside the spectacular revenue growth, CoreWeave reported a net loss of 709 million dollars for the quarter ended 30 September, widened from a loss of 110 million dollars a year earlier. Net interest expense rose to 846 million dollars in the same quarter. The company’s revenue backlog stood at 132.5 billion dollars at the end of September, which is the figure its supporters point to when they argue that the demand is real and contracted, not speculative. Its critics point to the debt. The tension between those two readings, a backlog that stretches years into the future and a balance sheet carrying the cost of building the data centres to serve it, is the central question hanging over the entire artificial intelligence infrastructure trade.
For one session, at least, the optimists won. The relief spread quickly through the whole ecosystem of companies that supply the artificial intelligence build-out. According to MarketWatch, shares of fellow neocloud company Nebius Group rose 15.4 per cent, Sandisk gained 13.7 per cent, Micron Technology jumped nearly 12 per cent and Dell rose 12 per cent. Optical stocks, which supply the components that move data inside data centres, were among the biggest winners: Lumentum Holdings rose 10.7 per cent, Coherent advanced 9.3 per cent and Marvell Technology gained 9.3 per cent. The iShares Semiconductor exchange-traded fund rose 6 per cent. In Europe, chipmaking equipment supplier ASML gained about 3 per cent, Dutch peer ASM International rose around 6 per cent and Germany’s Infineon climbed about 6.7 per cent, according to reports from Wednesday’s trading.
Jefferies trading-desk analyst Jeffrey Favuzza noted after CoreWeave’s earnings call that stocks in what he called the “AI-levered complex” were moving sharply higher, according to MarketWatch. The phrase captures how the trade has broadened: it is no longer only the handful of famous chip designers and cloud giants. It now includes memory makers, optical component suppliers, server assemblers and the power and cooling businesses that keep data centres running. When confidence in the trade wobbles, all of them fall together, as they did last week. When it returns, they rise together, as they did on Wednesday.
Nvidia recovers after losing about 430 billion dollars
Nvidia, the company at the centre of the artificial intelligence boom, also recovered. Its shares rose almost 3 per cent on Wednesday, according to MarketWatch, after two sessions of steep losses that had erased about 430 billion dollars of market value. The losses followed reports that its chief executive, Jensen Huang, may have been the target of a foreign intelligence operation linked to an alleged Chinese spy. Beijing called the accusations “groundless”, while Nvidia has said its board has no reason to believe American national security or company secrets were compromised and that Huang has committed to cooperating with an internal review.
Nvidia’s independent directors have hired former acting United States attorney Joon Kim and the law firm Wachtell, Lipton, Rosen & Katz to examine the matter, according to market reports. The episode is a reminder that the most valuable company in the world now carries risks that have nothing to do with its products: geopolitics, national security politics and the sheer scale of attention that comes with sitting at the centre of the rivalry between the United States and China over advanced technology.
The next test comes soon. Nvidia is scheduled to report its fiscal third-quarter results on 17 November, and that report is now the single most anticipated event on the market calendar. After Wednesday’s rebound, expectations are high again. If the numbers and the guidance disappoint, last week’s sell-off could resume quickly. If they are strong, they could settle the argument, for a while, about whether demand for artificial intelligence computing is durable.
The broader Asian rally on Wednesday was led by the same chip theme. MSCI’s broadest index of Asia-Pacific shares jumped 1.5 per cent for a third straight day of gains, according to Reuters, helped by a 2.6 per cent rise in South Korea and a 3.6 per cent increase in Taiwan. Taiwan’s Taiex gained 2.1 per cent, helped by a 3.1 per cent rise in TSMC, the world’s largest contract chipmaker, while South Korea’s Kospi rose 1.6 per cent to 5,321.10, with Samsung Electronics up 2.3 per cent and SK Hynix up 3.4 per cent, according to the Associated Press.
Europe’s quiet record
While the artificial intelligence rebound grabbed the headlines, Europe quietly set a record. The STOXX 600’s closing high of 663.05 points capped a rally that has attracted far less attention than the swings on Wall Street, but which may be the more significant development of the autumn. According to Reuters, the rally has been driven by rotation beyond artificial intelligence-related sectors: thirteen sectors out of twenty have outperformed the benchmark since the American midterm elections, according to Societe Generale. Solid third-quarter earnings and upgrades to the outlook for 2027, hopes of de-escalation in the Middle East and upgrades to German growth forecasts have all helped.
With roughly half of STOXX 600 companies having now reported, third-quarter earnings are tracking growth of around 24 per cent year on year, according to Nuveen, the asset manager. That is a strong number, but it is narrow growth. Energy accounts for almost half of it. Take energy and technology out, and the number falls to around 10 per cent. Nuveen calculates that energy, artificial intelligence-exposed technology and financials together account for roughly 85 per cent of aggregate earnings growth this quarter, despite representing a smaller share of the index by company count. The concentration is a warning as well as a cause for celebration: the record is real, but it rests on a small number of shoulders.
Germany, Europe’s largest economy, offered a small piece of good news of its own. Data on Wednesday showed German inflation slowed to 2.8 per cent in October, confirming a preliminary reading, according to Reuters. The figure sits above the European Central Bank’s two per cent target, but the direction of travel is downward, and that gives the central bank room to keep policy steady while growth recovers.
Conca, the Swiss wealth manager, told Reuters that the equity rally was broadening beyond the artificial intelligence-linked stocks that had led markets in recent years, with value sectors and Europe attracting new interest. He also said earnings growth remained robust enough to support equities despite pressure on valuations across parts of the artificial intelligence sector. Investors were also watching Anthropic, the artificial intelligence company, which is pressing ahead with its stock market listing at a valuation of 1.4 trillion dollars, according to Reuters, setting up a key test of Wall Street’s faith in the artificial intelligence boom. Underwriters led by Goldman Sachs and Morgan Stanley are considering raising the proposed price range following strong investor demand, the Financial Times reported.
King dollar and the road to 160 yen
The other great market story of the week has been the dollar. The American currency strengthened again on Wednesday, with the dollar index, which measures its performance against a basket of six major currencies, rising to 102.87, on pace for its highest close since April 2025, according to The Wall Street Journal. Reuters described it as a nineteen-month high, and noted that the index is five per cent higher than it was only a couple of months ago.
The most closely watched move was against the Japanese yen. The dollar rose 0.69 per cent to 159.84 against the yen, according to a Reuters report carried by Kitco, hitting its strongest level in more than two months and nearing the psychologically important mark of 160 yen per dollar. The Wall Street Journal reported that the greenback strengthened 0.6 per cent against both the euro and the yen. The euro dropped to 1.1082 dollars, its lowest level since May 2025, according to LSEG data cited by the Journal.
The 160 level matters because it is widely considered to be “intervention territory” for the Japanese authorities, as Reuters put it. Japan has intervened in the currency market before when the yen has weakened sharply, selling dollars and buying yen to slow the slide. A sustained move above 160 would raise the prospect of official action, and traders are watching for any sign of what the Japanese call “jawboning”, verbal warnings from officials designed to cool speculative selling of the yen. So far, Reuters noted, there has been no jawboning from Tokyo or Washington, and the move appears to be based on fundamentals rather than speculation.
Those fundamentals are straightforward: American interest rates are heading up while Japanese rates remain low, and the gap between them makes holding dollars more attractive than holding yen. The Bank of Japan is also considering further monetary tightening, and its October Summary of Opinions revealed increasing support for another rate rise in December, although policymakers remain divided over the pace, according to market reports. But even if the Bank of Japan raises rates in December, the gap with American rates will remain wide, and that gap will keep pulling the yen lower.
The dollar’s strength has a flip side. A strong dollar makes American exports more expensive, squeezes the profits that American multinationals earn overseas when they are converted back into dollars, and raises the cost of servicing dollar-denominated debt for borrowers in emerging markets. It also, paradoxically, tends to push down the price of commodities priced in dollars, which is one reason gold fell below 4,000 dollars an ounce on Wednesday, down one per cent, according to Reuters. Gold had bounced 0.4 per cent to 4,047 dollars an ounce earlier in the session, recovering some ground after a 2.6 per cent slide in the previous session when a stronger dollar and hawkish Federal Reserve remarks weighed on the precious metal.
Oil moved the other way. Brent crude rose 1.4 per cent to 92.8 dollars a barrel, rebounding from two-month lows after Tehran said it would not allow even a single particle of enriched nuclear material to leave the country, reducing hopes of an imminent de-escalation in the war between the United States and Iran, according to Reuters. The oil market remains hostage to that conflict, and every statement from Tehran or Washington can move prices by a dollar or more in either direction.
The rate-hike shadow has not gone away
None of Wednesday’s celebration should obscure the fact that the reason markets fell on Tuesday has not gone away. Data released on Tuesday showed that American consumer prices rose 0.4 per cent in October, above the forecast of 0.3 per cent, while core inflation, which excludes volatile food and energy prices, rose 0.3 per cent, above the forecast of 0.2 per cent. It was the third consecutive month in which inflation came in hotter than economists expected.
Before the data landed, Federal Reserve Governor Christopher Waller had said that he would support a 25-basis-point rise in December, but that a 50-basis-point increase “should be considered” if core inflation came in at 0.3 per cent or higher. The data then delivered exactly the number he had named. Dallas Federal Reserve President Lorie Logan said two more rate rises were needed, Chicago Federal Reserve President Austan Goolsbee warned of a “real inflation issue”, and Philadelphia Federal Reserve President Anna Paulson called for gradual rate hikes, according to Reuters.
Money markets responded by pricing in an 88 per cent chance of a 25-basis-point increase at the Federal Reserve’s December meeting and a 12 per cent chance of a 50-basis-point move, according to LSEG data cited by The Wall Street Journal. The CME FedWatch Tool put the odds at roughly 85 per cent for a quarter-point rise and 15 per cent for a half-point rise. Perhaps more striking is what has happened to expectations for January: the chance of another 25-basis-point increase at that meeting has surged to 60 per cent, compared with just 19 per cent before Tuesday’s repricing. Some brokerages have revised their forecasts accordingly. Goldman Sachs now expects rate rises in December and March, while Deutsche Bank expects rises in December, January and March. Traders now see close to 75 basis points of tightening by September next year, according to LSEG data.
The bond market has felt the shift most sharply. The yield on the ten-year Treasury note climbed to 4.99 per cent, close to five per cent, and the two-year yield jumped 18 basis points on Tuesday. American bond markets were closed on Wednesday for the Veterans Day holiday, which meant that the equity rally unfolded without the usual anchor of live Treasury trading. European yields were steady, while Japanese yields rose slightly, with the ten-year Japanese government bond yield up 10 basis points to 2.793 per cent, according to Reuters.
Reuters columnist Mike Dolan, writing in the Trading Day column, questioned the logic of the Federal Reserve’s emerging path. “To go from a 25 bps hike in September to a pause in October, then a 50 bps hike in December, doesn’t make sense,” he wrote, describing the communication coming out of the Federal Reserve as confusing. Inflation may be sticky, he argued, but that has been known for a long time. The criticism points to a deeper problem: when a central bank’s signals swing from meeting to meeting, markets cannot plan, and every new piece of data becomes a potential trigger for a violent repricing.
Analysis: Why It Matters
Wednesday’s rebound was a genuine relief rally, but it was also a revealing one. It showed what the market is really afraid of, what it is prepared to forgive, and how thin the line has become between confidence and panic in the most expensive stock market in modern history. Five points stand out.
1. One earnings call can still move the world
The most remarkable feature of Wednesday’s trading was how much of it turned on a single company that most people outside financial markets had never heard of a year ago. CoreWeave is not Nvidia. It is not Microsoft or Alphabet. It is a young, loss-making infrastructure business that rents out computing power. Yet its results moved stock markets in New York, London, Frankfurt, Tokyo, Seoul and Taipei, because it answered the one question that had been hanging over every artificial intelligence stock since last week’s sell-off: is the demand real?
The answer, on the evidence of a 168 per cent rise in quarterly revenue and a contracted backlog of 132.5 billion dollars, appears to be yes. But the episode also exposes a fragility. When the entire market’s confidence rests on the order books of a handful of infrastructure companies, each earnings season becomes a referendum on the whole trade. That is a precarious way to value the largest companies in the world. A single disappointing report, from Nvidia on 17 November or from any of the big cloud providers in the next cycle, could reverse Wednesday’s gains just as quickly as CoreWeave’s report produced them. The market has become a serial monogamist, falling in and out of love with the artificial intelligence story on the strength of each new data point.
2. The market is buying growth and ignoring the rate risk, for now
The second striking feature of Wednesday was what investors chose not to worry about. The case for a December rate rise is now, by the market’s own pricing, essentially settled, and the chance of a half-point move has risen from negligible to roughly one in seven. The dollar is at a nineteen-month high. The ten-year Treasury yield is knocking on five per cent. A year ago, any one of those facts would have been enough to send technology stocks sharply lower, because higher rates reduce the present value of future earnings, and technology companies are valued precisely on earnings that lie years in the future.
On Wednesday, investors bought technology stocks anyway. There are two ways to read that. The generous reading is that the market believes the economy is strong enough to absorb higher rates, and that artificial intelligence earnings growth will outrun the drag of tighter money. The less generous reading is that the market is simply choosing to look at the good news and defer the bad news, a habit that has preceded most corrections. The truth is probably a mixture of both. Growth is real, and so is the rate risk, and the market will keep swinging between the two until one of them produces a decisive piece of evidence. The Federal Reserve’s December meeting, and the data that arrives before it, will supply that evidence one way or the other.
3. Europe’s record deserves more attention than it gets
The STOXX 600’s record close attracted far less coverage than the artificial intelligence rebound, and that is a shame, because it may be the more durable story. Europe’s rally has been broad, with thirteen of twenty sectors outperforming since the American midterms, and it has been built on earnings rather than on a single theme. That breadth matters. A rally led by one sector can reverse in a week. A rally built on earnings growth across energy, banks, industrials and technology has deeper foundations.
But the concentration of that earnings growth should temper the celebration. When almost half of the growth comes from energy and 85 per cent from three sectors, the record is vulnerable to a single shock, whether a fall in oil prices, a squeeze on bank margins or a slowdown in the artificial intelligence supply chain. Europe has spent years being dismissed as the market that never quite recovers. This autumn it has finally recovered. Whether it can hold the gains will depend on whether the breadth of the rally widens further, or whether it narrows back to the same few names that dominate everywhere else.
4. King dollar is a double-edged sword
The dollar’s rise to a nineteen-month high is the most consequential market move of the week for the world outside the United States, and it cuts both ways. For American consumers it is good news, because a strong dollar makes imports cheaper and helps to hold down inflation. For the rest of the world it is a tax. Borrowers in emerging markets who owe dollars find their debts heavier. Exporters who compete with American firms find their goods relatively more expensive. And Japan, the world’s fourth-largest economy, finds itself pushed towards the 160 yen line where its government has intervened before.
The intervention question is the one to watch. Japan has spent billions in past episodes defending the yen, and the authorities have shown they will act when they judge a move to be disorderly. But intervention against a move driven by fundamentals, a genuine gap in interest rates, is expensive and usually only buys time. The durable solution would be for the Bank of Japan to raise rates faster, or for the Federal Reserve to stop raising them. Neither looks likely in the near term, which means the pressure on the yen is likely to persist, and with it the risk of a sudden, disorderly adjustment if Tokyo does decide to act.
5. The Federal Reserve has a credibility problem of its own making
The sharpest criticism of the week came not from a trader but from a Reuters columnist, and it was aimed at the Federal Reserve itself. A quarter-point rise in September, a pause in October, and now the prospect of a half-point rise in December is, as Mike Dolan wrote, a sequence that “doesn’t make sense”. The point is not that the Federal Reserve is wrong to worry about inflation. The October data, the third consecutive upside surprise, gives it every reason to worry. The point is that its communication has made the worry worse.
When Governor Waller publicly attaches a half-point rise to a single monthly inflation number, he turns every data release into a potential policy shock. When different officials give different signals within days of each other, markets cannot tell what the institution thinks. The result is exactly what happened this week: a violent repricing on Tuesday, a relief rally on Wednesday, and a market that is now pricing in nearly three quarters of a percentage point of tightening by next September while simultaneously buying the stocks that such tightening should hurt. A central bank’s most valuable asset is predictability. The Federal Reserve has spent the autumn spending it, and it will need to rebuild it before December, or the volatility of this week will become the pattern of the winter.
What to Watch Next
- Nvidia’s results on 17 November: the single most important earnings report of the quarter. Strong numbers and guidance would validate Wednesday’s rebound; a disappointment could restart last week’s sell-off across the whole artificial intelligence complex.
- The 160 yen line: whether the dollar breaks decisively above 160 yen, and whether Tokyo responds with verbal warnings or actual intervention in the currency market.
- Federal Reserve speakers on Thursday: Beth Hammack, Michael Barr, Austan Goolsbee, Mary Daly, Jeffrey Schmid, John Williams and Philip Jefferson are all scheduled to speak. Any of them could clarify, or further confuse, the December outlook.
- Britain’s third-quarter GDP figures: due on Thursday, they will show whether the British economy is holding up under high borrowing costs and ahead of the Chancellor’s budget questions over growth.
- The thirty-year Treasury auction: the United States Treasury sells 22 billion dollars of thirty-year bonds on Thursday. Weak demand would push long-term yields higher and test the equity rally.
- Anthropic’s listing: pricing of the 1.4 trillion dollar artificial intelligence flotation will test whether investor appetite for the sector extends beyond the public markets.
- Producer prices on 13 November and the jobs report on 4 December: the next two big data releases before the Federal Reserve’s decision on 9 December, when markets will learn whether the rise is 25 basis points, 50, or something else entirely.
Sources
- Reuters — Trading Day: AI cheer banishes rate hike fear
- Reuters via Devdiscourse — Global Markets: Tech lifts world stocks as CoreWeave revives AI trade
- MarketWatch — CoreWeave just gave a shot in the arm to Micron, Lumentum and the rest of the AI trade
- The Wall Street Journal — Dollar Rises to 19-Month High on Fed Rate-Hike Bets
- Reuters via Kitco — Dollar climbs as traders raise December Fed hike bets
- Reuters via Devdiscourse — Global Markets: Stocks gain as CoreWeave reignites AI trade

About the Author — Abdul Mannan
Related Articles
Nvidia Loses $430 Billion in Two Days as $7.5 Billion China Chip Claim and a Resignation Call Deepen the Huang Crisis
Nvidia has lost about $430 billion in market value in two days as a report alleged Jensen Huang's…
Hot October Inflation Puts the Fed on Course for a December Rate Hike — and a Half-Point Move Is Now on the Table
US consumer prices rose 0.4% in October and core inflation held at 0.3% for a third straight month,…
Vodafone Lifts Full-Year Guidance as Business Division Hits Record Growth Despite €3.6 Billion Loss on German Writedown
Vodafone raised its full-year profit and cash flow guidance after a strong first half driven by record business…