
Wall Street Ends a Wild Week Lower as Nvidia’s Slide Deepens and Chip Stocks Plunge

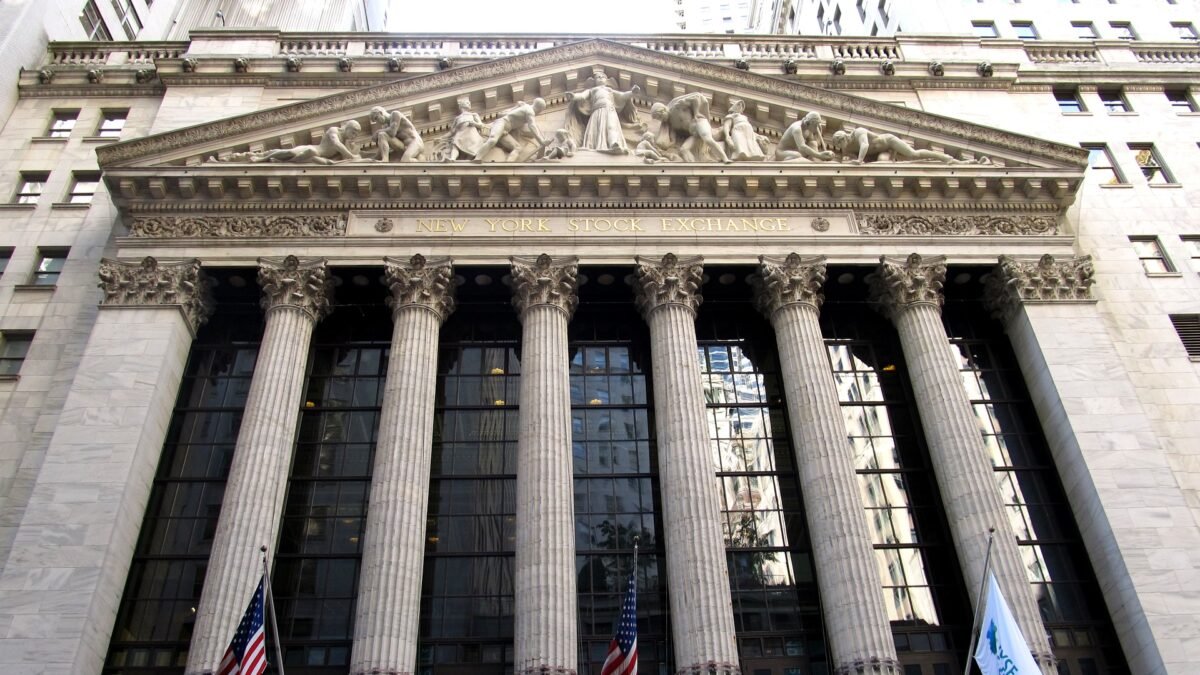
Wall Street closed lower on Friday as the crisis at Nvidia deepened into a second day of heavy selling, dragging chip stocks down across the board and leaving the technology-heavy Nasdaq with its sharpest daily fall of the week. Yet the session ended with a paradox that summed up a wild week: despite two days of declines, all three major indexes finished with their strongest weekly gains since early August.
According to the Associated Press, the S&P 500 fell 30.73 points, or 0.4 per cent, to close at 7,561.67 on Friday, while the Nasdaq Composite dropped 229.82 points, or 0.91 per cent, to 25,136.27. The Dow Jones Industrial Average went the other way, edging up 50.46 points, or 0.10 per cent, to 52,347.55. The split between the indexes told the story of the day: technology led the retreat, while older-economy sectors such as consumer staples and energy held the Dow above water.
Nvidia, the company at the centre of the week’s turmoil, fell 2.0 per cent to close at $162.85, according to market reports. The shares had dropped by almost 5 per cent in morning trading before recovering some ground, and the stock has now lost about 12 per cent of its value across the week. It was the sixth consecutive weekly decline for the shares, their longest such run since October 2012, and the company’s market value slipped below $4 trillion for the first time in the current sell-off, according to Yahoo Finance data cited in market coverage.
The fall came a day after Nvidia’s shares had already plunged 4.3 per cent on Thursday to close at $166.19, in the first full session after co-founder Jensen Huang resigned as chief executive. In two sessions, the stock has given up more than 6 per cent, and according to Reuters, more than $2 trillion of market value has been erased in a little over a month. A weekly market review put the damage for the week alone at just under $600 billion.
A chip sell-off that spread far beyond Nvidia
Friday’s damage was not confined to Nvidia. The Philadelphia Semiconductor Index fell 3.4 per cent, and the iShares Semiconductor exchange-traded fund dropped 4.3 per cent, according to Investor’s Business Daily. Advanced Micro Devices tumbled 8.8 per cent to close at $534.06, making it the worst-performing stock in the S&P 500 on Friday, according to market data. Broadcom fell 4.8 per cent, Marvell Technology dropped nearly 5 per cent, and Intel and Micron each declined 2.5 per cent.
The selling reached the companies that build and supply the artificial-intelligence infrastructure Nvidia’s chips power. Applied Materials lost 3 per cent despite reporting better-than-expected quarterly earnings. Dell Technologies fell about 7 per cent. CoreWeave, one of the cloud companies backed by Nvidia, fell about 6 per cent, while Nebius dropped about 10 per cent. Optical component makers Coherent and Fabrinet each slid about 8 per cent, according to Benzinga.
Even companies reporting good news were not spared. Cisco Systems fell about 6 per cent, erasing roughly $26 billion of its market value, even after the networking company reported strong quarterly results and raised its outlook on growing demand for artificial-intelligence infrastructure. According to Benzinga, a squeeze of 250 basis points in Cisco’s adjusted gross margin overshadowed the record first-quarter revenue and the higher fiscal 2027 outlook.
The pattern of the day was a reversal of Thursday’s trade. On Thursday, investors had rushed out of Nvidia and into rival chipmakers: AMD had risen more than 5 per cent and Broadcom had gained 5.5 per cent in that session. On Friday, that rotation unwound violently. AMD gave back its entire Thursday gain and more, and Broadcom surrendered its advance too. As one market report put it, traders were unwinding the week’s rush out of Nvidia and into rival chipmakers, and the rush itself became the casualty.
Not every technology name fell. Apple rose 0.4 per cent to a record closing high, and Microsoft edged higher as the global outage affecting its Outlook and Teams services began to ease, according to AsiaToday. Alphabet also advanced more than 1 per cent in early trading. But the gains in the largest names were not enough to offset the breadth of the decline in semiconductors: declining stocks outnumbered advancers by about eight to five on the Nasdaq, according to Investor’s Business Daily, although slightly more stocks rose than fell on the New York Stock Exchange.
Inflation data fails to calm rate fears
The sell-off came despite a cooler-than-expected inflation reading. The United States Labor Department said on Friday that the producer price index, which measures the prices businesses receive for their goods and services, rose 0.3 per cent in October, below the 0.4 per cent forecast by economists. But the annual rate reached 6.5 per cent, its highest since November 2022, according to AsiaToday.
The report did little to change expectations that the Federal Reserve will raise interest rates again at its December meeting. Markets have fully priced in a quarter-point increase in December, with roughly a 10 per cent chance of a larger half-point move, according to CME FedWatch data cited in market coverage. The yield on the 10-year Treasury rose to 5.15 per cent, up from 5.13 per cent at Thursday’s close, according to AsiaToday.
Several Federal Reserve officials reinforced the hawkish message on Friday. San Francisco Fed President Mary Daly said her bias was for the central bank to increase its policy rate, and Boston Fed President Susan Collins said tighter monetary policy was coming because of high inflation. Their comments followed a week in which Cleveland Fed President Beth Hammack had said the Fed needed to move to a restrictive stance to bring inflation back to 2 per cent, preferring “more frequent, smaller rises”, according to Reuters.
The producer price figures matter because they arrived in a week when the market was already anxious about the direction of borrowing costs. A 6.5 per cent annual rise in producer prices is the largest in four years, and it sits uncomfortably alongside a Federal Reserve that has been signalling that its next move is more likely to be up than down. For technology stocks, whose valuations depend heavily on expectations about future earnings discounted at current interest rates, a rising-rate outlook is a direct headwind. That helps explain why the chip sell-off accelerated on a day when the inflation data, on its face, looked slightly better than expected: the monthly number was reassuring, but the annual number was not.
The Bloomberg report that deepened the Nvidia scandal
Investors also digested a new report from Bloomberg News that traced restricted Nvidia chips to a data centre in Shanghai linked to a company founded by Alice Huang, the woman at the centre of the affair allegations that preceded Jensen Huang’s departure. According to the report, 22 servers built by Dell and containing Nvidia H800 chips, which are banned from sale in China, were sold to Aperia Cloud Services, an Nvidia cloud partner based in Singapore, before being installed at the Yangtze River Delta Project facility in Shanghai.
Dell ended its business relationship with Aperia in February 2025 because of concerns about the transaction, according to the report. The hardware details came from filings by Shanghai Longteng Intelligent Computing, a company set up by Alice Huang about a decade ago, which listed the servers as collateral for financing. The filings also showed 52 servers made by Super Micro Computer equipped with H100 or H200 chips, which also cannot be sold to Chinese companies without permission from the United States government. The documents did not say whether Alice Huang was personally involved in obtaining the chips, and she has not been part of Shanghai Longteng since 2017, according to the report.
Treasury Secretary Scott Bessent said on Friday that the Treasury had favoured blacklisting Megaspeed, the Singapore-based Nvidia partner where Alice Huang previously held a senior role. “The real story here should be, did Nvidia know their client,” Bessent told CNBC. Beijing has denied that Alice Huang acted as a spy, and Nvidia’s board has said it has no reason to believe that national security interests or company secrets were compromised.
The report landed on top of a week of revelations that have already transformed Nvidia from a market story into a Washington story. The company’s former chief executive has agreed to testify before Congress, and the House Foreign Affairs Committee, the Intelligence Committee and the Select Committee on China are preparing a joint closed-door briefing. The Federal Bureau of Investigation has attributed the theft of more than $6 billion of cryptocurrency from Binance to a North Korean hacking unit, but that is a separate matter; the Nvidia questions now centre on export controls, on what the company’s board knew, and on whether restricted chips reached China through intermediaries.
According to the Financial Times, Nvidia’s board has approached Rene Haas, chief executive of British chip designer Arm Holdings, as a possible successor to Huang. The company has not confirmed the approach, and the search for a permanent chief executive is expected to take time. In the meantime, chief financial officer Colette Kress is serving as interim chief executive, and she will present the company’s third-quarter results on Tuesday, its first earnings report without Huang at the helm.
The week still ended higher
Despite two days of declines, the major indexes finished the week firmly higher. The S&P 500 gained 2.5 per cent for the week and the Nasdaq rose 2.3 per cent, ending four-week losing streaks for both, while the Dow added 2.1 per cent. According to the Associated Press, it was the best weekly performance for each index since the week of 3 August. The S&P 500 added 184.81 points over the week, the Nasdaq 556.85 points, and the Dow 1,061.82 points.
The weekly gain is a reminder of how the week began. On Monday, markets rebounded sharply from the artificial-intelligence sell-off of the previous week, and the rally carried through the middle of the week before the Nvidia news broke on Thursday. The Philadelphia Semiconductor Index, despite falling 3.4 per cent on Friday, surged 8.05 per cent over the week as a whole, according to a weekly market review, outperforming the broader market by a wide margin. The damage of Thursday and Friday, in other words, was concentrated in the final two sessions of an otherwise strong week.
Elsewhere in the markets, the rotation away from technology was visible in the sectors that gained. Consumer staples rose 1.39 per cent and energy rose 0.96 per cent on Friday, according to Xinhua News Agency, while the technology sector declined 1.7 per cent, the largest drop among the eleven major S&P sectors. Six of the eleven sectors rose on the day. Oil prices held broadly steady: West Texas Intermediate crude settled at $88.56 a barrel, down 0.2 per cent, while Brent crude settled at $95.84 a barrel, according to market data. Gold futures edged lower to $3,875 an ounce.
Bitcoin traded at $68,300, extending a month-long slide that has left the cryptocurrency about 20 per cent lower, according to AsiaToday. The decline in digital assets has run alongside the retreat in technology shares, and both reflect the same shift in sentiment: investors are pulling back from the highest-risk, highest-growth corners of the market while they wait for clarity on interest rates and on the leadership of the world’s most important chip company.
Why the market can fall and rise in the same week
The week’s split personality is easier to understand once the calendar is laid out. Monday’s rebound was a reaction to the previous week’s sell-off, when artificial-intelligence stocks had been hit by a wave of selling. Tuesday and Wednesday brought a steadier tone, with investors buying back into the market and the indexes recovering ground. Then, on Thursday, the Nvidia board accepted Huang’s resignation, and the market’s attention snapped back to the single company that has come to stand for the entire artificial-intelligence trade.
Thursday’s session was violent: Nvidia fell as much as 14 per cent during the day before recovering to close down 4.3 per cent. Friday was the aftershock. The morning’s near-5 per cent fall in Nvidia, the plunge in AMD and Broadcom, and the drop in the semiconductor index all pointed to the same thing: investors were not just selling one stock, they were repricing the risk of owning the whole artificial-intelligence complex without knowing who will run its most important company, what Congress will ask, and what else the export-control investigation will find.
The producer price data added a second layer of anxiety. A 6.5 per cent annual increase in wholesale prices is not the kind of number that lets a central bank pause, and the Federal Reserve’s own officials spent the week saying so. The market has now fully priced in a December rate rise, and a minority of traders are betting on a half-point move. Higher rates are bad news for growth stocks in general and for chipmakers in particular, because their valuations assume years of future earnings that are worth less when discounted at higher rates.
That combination, a governance crisis at the market’s bellwether and a hawkish central bank, is what turned a strong week into a weak finish. The indexes held their weekly gains because the first three days of the week were strong enough to absorb the last two. But the direction of travel into the weekend was unmistakably down, and the questions that drove the selling are still unanswered.
Analysis: Why It Matters
The AI trade now has a governance discount
For three years, Nvidia has been the market’s shorthand for artificial intelligence itself. Its chips power the data centres, its earnings set the tone for the sector, and its chief executive was treated as the industry’s most reliable prophet. The events of this week have broken that shorthand. Investors are no longer pricing Nvidia on its technology alone; they are pricing it on the uncertainty around its leadership, on the congressional testimony to come, and on the possibility that export-control problems run deeper than the board has admitted.
That is what a governance discount looks like. The company’s technology has not changed in the past week. Its data-centre customers have not cancelled their orders. Its order book, as far as anyone knows, is intact. What has changed is the confidence investors place in the people running it, and confidence is the one asset a stock market cannot value on a spreadsheet. Until a permanent chief executive is named and the congressional process has run its course, Nvidia is likely to trade at a discount to the valuation its fundamentals alone would support.
The rotation into rivals failed its first test
Thursday’s trade was elegant in theory: sell Nvidia, buy AMD and Broadcom, and keep exposure to the chip cycle while escaping the scandal. It lasted one session. On Friday, AMD became the worst-performing stock in the entire S&P 500, and Broadcom fell almost 5 per cent. The lesson is that the chip trade is not a set of interchangeable parts. Nvidia’s rivals rose on Thursday because investors assumed the scandal was contained to one company; they fell on Friday because investors concluded it was not.
The Bloomberg report is the reason. If restricted chips reached a Shanghai data centre through a Singapore intermediary, the problem is not one company’s governance but the plumbing of the entire export-control system. That implicates Dell, Super Micro, the cloud partners, and the regulators who were supposed to police the flow of advanced chips. A scandal that touches the system cannot be traded around by switching from one chipmaker to another, and Friday’s selling was the market working that out in real time.
Inflation is doing the Fed’s arguing for it
The producer price report deserves more attention than it received on Friday. An annual rate of 6.5 per cent is the highest in four years, and it arrived in the same week that three Federal Reserve officials publicly argued for higher rates. The market has now fully priced in a December increase, and the debate has moved on to whether the rise will be a quarter point or a half point.
This matters beyond the chip sector. Higher rates raise the cost of capital for every company, and they make the future earnings that justify high technology valuations worth less today. The chip sell-off and the inflation data are not two separate stories; they are the same story told twice. A market that was already nervous about the price of money found a reason to sell the stocks most sensitive to it, and the producer price figures supplied that reason on a day when the market was looking for one.
Tuesday’s earnings are the next real test
Nvidia reports third-quarter results on Tuesday, and the numbers will be read in a way no Nvidia earnings report has ever been read before. Analysts expect revenue growth of about 92 per cent for the October quarter and net profit above $60 billion, according to Reuters and LSEG data. Those are extraordinary figures by any standard. But the market will not be listening only for the numbers.
It will be listening for what interim chief executive Colette Kress says about the export-control questions, about the board’s search for a permanent successor, and about whether the scandal has affected customer orders or the company’s relationships with its cloud partners. A strong earnings report that ducks those questions will not be enough. The company needs to show that its business is intact and that its governance is under control, and Tuesday is the first opportunity to do either in public.
A strong week with a weak ending is a warning, not a verdict
It is worth remembering that the week ended higher. The S&P 500 gained 2.5 per cent, the Nasdaq 2.3 per cent, and the Dow 2.1 per cent, the best weekly performance for each since early August. Four-week losing streaks were broken. The breadth of Friday’s session was not catastrophic: six of the eleven S&P sectors rose, and the Dow finished in positive territory.
But the direction of the final two sessions matters more than the weekly total. Markets remember how a week ends, and this one ended with the market’s most important stock at a fresh 52-week low, with its chief executive gone, with Congress preparing questions, and with the central bank signalling higher rates. The weekly gain was earned in the first three days, before any of that was known. Whether it survives the coming week depends on Tuesday’s earnings, on the succession search, and on whether the export-control story stops growing. None of those questions has an answer yet, and that is precisely why the selling was so broad.
What to Watch Next
- Nvidia’s third-quarter results on Tuesday: the company’s first earnings report without Jensen Huang, presented by interim chief executive Colette Kress, with analysts expecting revenue growth of about 92 per cent and net profit above $60 billion, according to Reuters and LSEG.
- The succession search: whether the board confirms or denies the Financial Times report that it has approached Arm chief executive Rene Haas, and how quickly a permanent chief executive is named.
- Congressional testimony: the date and format of Huang’s appearance before the House Foreign Affairs, Intelligence and China committees, and whether the briefing is public or closed-door.
- The export-control investigation: whether the Commerce Department or the Justice Department takes action on Megaspeed, Aperia Cloud Services, or any other intermediary named in the Bloomberg report, and what the investigation finds about how restricted chips reached Shanghai.
- Anthropic’s market debut: the artificial-intelligence company’s listing next week, which will test investor appetite for established AI companies as money shifts towards the new entrant.
- The Federal Reserve’s December meeting: whether the producer price data and the officials’ comments push the market’s pricing of a half-point rise above its current level of about 10 per cent.
- Whether the chip rotation reverses again: whether AMD, Broadcom and the other rivals recover their Friday losses, or whether the sell-off spreads further into the artificial-intelligence supply chain.
Sources
- Associated Press — “S&P 500 falls 0.4% as Nvidia turmoil weighs on tech stocks”
- Investor’s Business Daily — “Stock Market Today: Indexes Trim Losses, Manage To Score Weekly Gains Despite Strong Volatility”
- AsiaToday — “Nvidia Selloff Drags Wall Street Lower Friday”
- Reuters via The Hindu BusinessLine — “US stocks fall as Nvidia slides 4.3%; Nasdaq drops 1.74%”
- NiftyTrader — “Chip Stocks Lose 3.4% as Nvidia’s Leadership Change Rattles”
- U.S. Bureau of Labor Statistics — Producer Price Index news release

About the Author — Abdul Mannan
Related Articles
Poundland Wins Ten Days to Find a Buyer as MPs Accuse US Owner Gordon Brothers of Starving the Chain of Cash
Poundland has won ten more working days to find a buyer after filing a second notice of intention…
India’s Inflation Breaches the Reserve Bank’s 6% Ceiling for the First Time in Two Years as Food Prices Surge
India's retail inflation rose to 6.09 per cent in October, breaching the Reserve Bank of India's 6 per…
Nvidia Plunges to a 52-Week Low as Huang’s Exit Shakes Wall Street While Oil Surges on Trump’s Iran Remarks
Nvidia shares plunged to a 52-week low on Thursday after Jensen Huang's resignation, while Brent crude jumped 3.3…