
Nvidia Plunges to a 52-Week Low as Huang’s Exit Shakes Wall Street While Oil Surges on Trump’s Iran Remarks

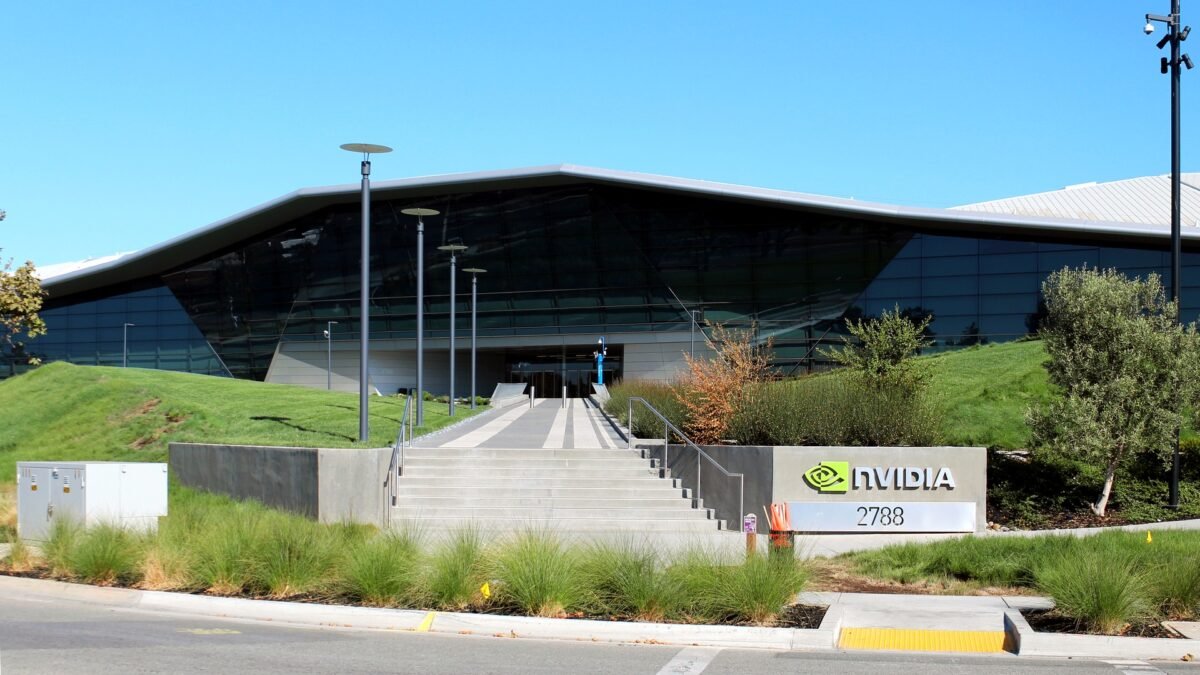
Wall Street endured one of its wildest trading days of the year on Thursday, as Nvidia shares plunged to a 52-week low in the first minutes of trading after the resignation of Jensen Huang, its chief executive, before recovering much of the loss — while oil prices surged after President Donald Trump said the United States no longer needs a deal with Iran. The twin shocks left the three main American indexes modestly lower, pushed the yield on the 10-year Treasury above 5.1 per cent, and underlined how quickly the market’s two great obsessions of 2026 — the artificial intelligence boom and the war in the Middle East — can turn on a single headline.
According to the Associated Press, the S&P 500 fell 26.98 points, or 0.35 per cent, to 7,592.40. The Dow Jones Industrial Average lost 189.40 points, or 0.36 per cent, to 52,297.09, and the Nasdaq Composite sank 100.10 points, or 0.39 per cent, to 25,366.09. The closing figures, however, told only half the story. At the open, the S&P 500 had dropped nearly 1 per cent and the Nasdaq had fallen 1.6 per cent, before buyers stepped in and erased most of the damage by the close.
The focus, according to the Associated Press, was squarely on Nvidia. Its shares plunged 14 per cent at the start of trading following the resignation of Huang, the company’s co-founder, chief executive and public face. The stock opened at $151.00, fell within five minutes to an intraday low of $148.80 — a fresh 52-week low and nearly 39 per cent below its record high of $243.37 set on 6 October — and then clawed its way back to close at $166.19, a fall of 4.3 per cent on the day, according to market data published by Finnhub. The previous 52-week low had been $164.27, set on 30 March.
Oil provided the day’s second shock. Brent crude, the international benchmark, climbed 3.3 per cent to settle at $95.82 a barrel, and West Texas Intermediate rose 2.6 per cent to $88.74 a barrel, according to the Wall Street Journal and Bloomberg. The rally began after Mr Trump wrote on his Truth Social platform that the United States does not need an agreement with Iran to end the war that began in late February. “We don’t need a deal with Iran. Those days have long since passed. We’ve got their money, Hundreds of Billions of Dollars, and we’ve got their Strait!” Mr Trump wrote, according to the Associated Press.
The two moves collided in the bond market. The yield on the 10-year Treasury jumped to 5.12 per cent from 4.98 per cent late on Tuesday, according to the Associated Press, after trading had been closed on Wednesday for Veterans Day. Higher oil prices feed worries about inflation, and higher yields make borrowing more expensive for everyone — from the government to companies building AI data centres to households buying homes.
A Brutal Open, Then a Partial Recovery
The scale of Nvidia’s opening fall was extraordinary even by the standards of a stock that has become the market’s single most important security. According to Reuters, more than $2 trillion in market value has been erased from Nvidia in a little over a month since its record high on 6 October. At the worst of Thursday’s open, the drop was on track to erase roughly $440 billion in a single day, according to Yahoo Finance, cited in market commentary.
Nvidia’s decline did not begin on Thursday. According to the Associated Press, the shares had already fallen 27 per cent from their record through Wednesday’s close. At first, the slide reflected worries that valuations across the AI industry had run too high. More recently, it has been driven by doubts about whether Huang would remain as chief executive and how Nvidia would navigate a future without him. The board answered the first question on Thursday morning, when it said Huang had resigned and named Chief Financial Officer Colette Kress as interim chief executive, according to the Associated Press. The second question remains unanswered.
Yet the recovery in the second half of the session was almost as striking as the fall. Nvidia quickly halved its early loss, and the broader market followed. According to Reuters, the S&P 500 is only around 3 per cent below its all-time high despite the turmoil in AI stocks, and the equal-weighted version of the index — which gives every company the same importance instead of letting the biggest dominate — hit a record high last week and is up nearly 5 per cent since 6 October. The message from the tape was that the average American company is holding up well, even as the market’s biggest star stumbles.
“This is a key-person event, not a demand event. Nobody is cancelling GPU orders because the CEO resigned. Historically, stocks take time to find a bottom after an abrupt CEO exit while the market works through the investigations and the search,” Erik Kratz, co-head of wealth and chief investment officer at Arena Private Wealth in Chicago, told Reuters.
The Philadelphia Semiconductor Index offers a measure of how deep the damage in chip stocks has run. According to Reuters, the index suffered its second-biggest loss on record — a 12 per cent slide on 5 November — and at that point stood down almost 40 per cent from its June high. The AI trade that carried the market to record after record in recent years is now being repriced in real time.
The Oil Shock That Came Second
If Nvidia dominated the morning, oil owned the afternoon. Brent crude had been trading at around $92 a barrel before Mr Trump’s post, and rose to $95.18 in afternoon trading before settling at $95.82, according to the Associated Press and the Wall Street Journal. West Texas Intermediate settled at $88.74. The move was all the more notable because it came on a day when the US Energy Information Administration reported an unexpected 4.7 million barrel increase in American crude stockpiles last week, against market expectations of a small draw, according to the Wall Street Journal. Normally, a build in inventories of that size would push prices down. Instead, traders shrugged it off.
The reason is that the oil market in 2026 is no longer trading on inventories. It is trading on the war. According to the Associated Press, the price for the most actively traded Brent contract has veered sharply since the United States and Israel began the war with Iran in late February, bouncing between roughly $70 and $120 a barrel. Three days before Thursday’s jump, Mr Trump had suggested the eight-month war was nearing its end. His post on Thursday pointed in the opposite direction, and traders priced the risk premium back in within minutes.
The physical disruption behind the price is real. According to the Wall Street Journal, the International Maritime Organization said on Wednesday that it had verified more than 130 attacks on commercial vessels in the Strait of Hormuz since the war began on 28 February. Iran’s military said on Thursday that four oil tankers were hit by explosions in the strait after ignoring warnings, according to Reuters, and the International Energy Agency is due to publish its monthly oil-market report on Friday. OCBC, the Singapore bank, has maintained its year-end Brent forecast at $100 a barrel, citing tanker attacks, longer shipping routes and limited vessel availability, according to the Wall Street Journal.
Energy stocks were among the day’s winners. Marathon Petroleum climbed 2.5 per cent and ExxonMobil added 1.8 per cent, according to the Associated Press, as investors bet that higher crude prices would flow through to profits. On a day when the market’s technology giants were under pressure, oil was the hedge that worked.
Yields Jump as the Fed Turns Hawkish
The third force moving markets on Thursday was the Federal Reserve — or, more precisely, the growing conviction that the Fed will keep raising interest rates. The 10-year Treasury yield’s jump to 5.12 per cent was the bond market’s answer to a week in which almost every piece of news has pointed the same way: inflation is proving stickier than expected, and the central bank is losing patience.
Cleveland Federal Reserve President Beth Hammack added her voice on Thursday. According to Reuters, Ms Hammack said she does not believe the central bank needs to shift to more aggressive interest rate rises, but that it does need to move policy into restrictive territory to bring inflation back to its 2 per cent target. “My expectations are that we need to move to a restrictive stance of policy to help bring inflation back down to that 2% objective, which is critically important,” she said during an event at Ohio State University, according to Reuters. She added that she prefers “more frequent, smaller rises” because that is “less disruptive to the overall economy than moving in sharper, more aggressive movements”.
Ms Hammack has been one of the Fed’s most steadfast supporters of higher rates, according to Reuters. She dissented at the July and October meetings, when the Fed left its benchmark rate unchanged in the 3.75 to 4.00 per cent range, and voted in favour of a rise at the most recent meeting. The Fed is widely expected to raise rates by a quarter of a percentage point at its 8–9 December meeting, according to Reuters, and the debate now is about what comes after.
That debate has sharpened since Tuesday’s inflation data. Consumer prices rose 0.4 per cent in October, with core prices — which exclude food and energy — up 0.3 per cent for a third consecutive month, above the 0.2 per cent forecast. Federal Reserve Governor Christopher Waller had said before the release that if core inflation came in at 0.3 per cent or higher, “a 50 basis point hike in the policy rate should be considered at the December meeting”. Dallas Fed President Lorie Logan has called for at least two further quarter-point rises. Money markets are pricing in a December increase of 25 basis points as near-certain, with roughly a 10 to 15 per cent chance of a half-point move, according to CME FedWatch data reported this week.
The housing market is already feeling the squeeze. According to the Associated Press, high mortgage rates helped send sales of previously occupied American homes in October to their slowest pace in more than 16 years. A separate report on Thursday said slightly more US workers applied for unemployment benefits last week, although the number remains relatively low by historical standards, according to the Associated Press. The economy is slowing, but it is not breaking — which is precisely the combination that keeps the Fed hiking.
The Rotation Inside the AI Trade
One of the most revealing features of Thursday’s session was what happened inside the AI trade itself. Not every chip stock fell. According to the Associated Press, CoreWeave, which buys Nvidia chips and rents out access to them over the cloud, fell 6.9 per cent, and Micron Technology, which sells the memory that has been gobbled up in the AI frenzy, sank 1.6 per cent. But Broadcom rose 5.5 per cent and Advanced Micro Devices added 5.9 per cent, on hopes that rival chip companies will gain a competitive advantage from Nvidia’s troubles. Those two gains came close to offsetting the drop for Nvidia, which was the single heaviest weight on the S&P 500, according to the Associated Press.
The pattern suggests investors see the AI business expanding to other players rather than depending solely on Nvidia, according to the Associated Press. That is a significant shift in market psychology. For the past three years, Nvidia has been treated as a proxy for the entire AI boom — the company whose chips power nearly every large AI model, and whose earnings calls have moved the whole market. Thursday’s trading hinted that the market is beginning to imagine an AI industry in which Nvidia is the biggest player, but not the only one that matters.
Whether that imagination survives the next earnings season is another question. Nvidia reports quarterly results on Tuesday 17 November, and according to Reuters, analysts on average expect the company to report a 92 per cent surge in October-quarter revenue and a net profit of more than $60 billion, an 89 per cent increase on a year earlier, according to LSEG data. Investors will be watching whether that sharp growth can survive without Huang — and, perhaps more importantly, what Ms Kress says about the company’s outlook, which may matter even more than the results themselves, according to Reuters.
By one of Wall Street’s favourite measures, Nvidia now looks cheap. According to Reuters, the shares are trading at the equivalent of 12 times expected earnings — the lowest valuation since 2012, when the company was competing with Advanced Micro Devices to dominate the market for video-game graphics cards while struggling to find a foothold in tablets and mobile devices. But a low price-to-earnings ratio can also reflect doubts that expected earnings will materialise, according to Reuters, and analysts have so far maintained forecasts for strong profit growth on the assumption that demand for Nvidia’s chips will continue to outpace supply. Tuesday’s results will test that assumption in public for the first time since Huang’s departure.
The Man Who Built the AI Boom Is Gone
The human story behind Thursday’s market drama is as extraordinary as the numbers. Huang, 63, co-founded Nvidia in 1993 and built it from a maker of graphics cards for video games into the company at the centre of the artificial intelligence revolution. According to the Associated Press, its stock price set a record last month after soaring 1,722 per cent in four years, compared with a gain of nearly 109 per cent for the overall S&P 500 over the same period. He became, in the words of the Associated Press, one of the biggest evangelists of AI — and, for a time, the most valuable chief executive in the world.
His fall was astonishingly fast. According to Barron’s, Nvidia hired the law firm Wachtell, Lipton, Rosen & Katz and former acting US attorney Joon H. Kim to investigate its chief executive after reports emerged that he had two extramarital affairs — one with a woman alleged to be a spy working for Beijing, and another with an employee of the company. Calls for Huang to step down grew quickly this week, according to Barron’s, and the board announced his resignation on Thursday morning, effective immediately, with Ms Kress taking over as interim chief executive while the search for a permanent successor begins.
President Trump weighed in on Thursday with characteristic bluntness. According to Barron’s, he wrote on social media: “NOW THAT Nvidia CEO JENSEN HUANG, who has done a fantastic job, has resigned, there is only one man to take his place – TIM COOK of Apple. A Legend replaces a Legend!” Prediction markets, meanwhile, have already begun taking bets on the succession. According to Barron’s, Nvidia executive Ian Buck is the front-runner at 29 per cent odds, followed by Ms Kress at about 28 per cent, according to Polymarket.
Mr Trump’s post on Iran was not his only intervention on Thursday. According to the Associated Press, he also said he had asked Vice President JD Vance to investigate American cities and states run by Democrats, rather than pursuing a deal with Tehran. The remark, buried in a post about the war, was a reminder that the president’s domestic political agenda and his foreign policy are now being conducted in the same breath — and that markets must price both at once.
In stock markets abroad, indexes were mixed in Europe following a weaker finish in Asia, according to the Associated Press. Hong Kong’s Hang Seng fell 1.3 per cent, one of the world’s biggest moves of the day. Australian shares edged lower, with the S&P/ASX 200 down 0.07 per cent to 9,146.80, according to the Finance News Network. The Nvidia shock, in other words, was felt everywhere — but contained almost everywhere.
Analysis: Why It Matters
1. A key-person event, not a demand event — yet
The most important distinction in this story is the one drawn by Erik Kratz to Reuters: Huang’s resignation is a key-person event, not a demand event. Nobody is cancelling orders for Nvidia’s graphics processors because the chief executive resigned. The chips are still selling, the data centres are still being built, and the earnings expected on Tuesday are, on paper, spectacular. That is why the stock recovered half its opening loss within hours, and why the broader market finished the day only modestly lower.
But the distinction has a shelf life. A key-person event becomes a demand event if the company loses its way — if customers start to doubt that the next generation of chips will arrive on time, if the engineers who built the empire start to leave, or if the board’s search for a successor drags on for months while rivals court Nvidia’s biggest clients. The history of abrupt chief executive departures is not encouraging: as Kratz told Reuters, stocks take time to find a bottom after a sudden exit while the market works through the investigations and the search. The question for investors is not whether Nvidia’s products still work. It is whether the organisation that built them still works without the man who built the organisation.
2. The market has learned to live without its star
Perhaps the most remarkable feature of Thursday was how little damage the rest of the market suffered. A year ago, a 14 per cent opening plunge in Nvidia would have been expected to drag the entire market down with it. Instead, the S&P 500 fell 0.35 per cent, the equal-weighted index is at a record high, and money rotated into Broadcom, AMD and the oil majors. Reuters’ analysis makes the point plainly: so much for Wall Street’s concentration risk.
There are two ways to read this. The optimistic reading is that the market has genuinely broadened — that the AI boom has spread beyond a single company, and that the rally in the average stock is more durable than the rally in a handful of giants. The pessimistic reading is that the market is in denial, and that the real test comes when Nvidia reports earnings on Tuesday and investors must decide whether to believe the numbers without believing in the man who used to present them. Either way, Thursday proved that Wall Street can absorb a shock to its most important stock. What it has not yet proved is that it can absorb a shock to the AI story itself.
3. Oil is the market’s new volatility machine
For most of the past decade, oil was a sideshow for equity investors — a commodity that moved on OPEC meetings and inventory reports. In 2026, it has become a volatility machine driven by presidential social media posts and tanker attacks in the Strait of Hormuz. Brent has swung between roughly $70 and $120 a barrel since the war began, and Thursday’s 3.3 per cent jump came on a day when the fundamental news — a 4.7 million barrel build in American stockpiles — pointed the other way.
This matters for two reasons. First, oil is now a direct input into the inflation story that is driving the Federal Reserve. Every dollar on the price of crude makes the Fed’s job harder and a December rate rise more likely. Second, the oil market’s sensitivity to a single Truth Social post means that equity investors must now price a war they cannot predict, conducted in a medium they cannot model. The 130 verified attacks on commercial shipping in the strait are a physical fact; the president’s negotiating posture is a moving target. Markets hate that combination, and Thursday showed it.
4. The Fed’s credibility is now the trade
The bond market’s reaction to Thursday’s news was arguably more important than the stock market’s. The 10-year yield jumping above 5.1 per cent is not just a number; it is a verdict on the Federal Reserve’s credibility. Waller’s trigger for a half-point December rise — core inflation of 0.3 per cent or more — has been met. Logan wants at least two more quarter-point rises. Hammack, who dissented twice this year because she wanted rates higher, now says the Fed must move to a restrictive stance, even if she prefers to get there gradually.
The stakes are visible in the housing market, where sales of existing homes fell in October to their slowest pace in more than 16 years, according to the Associated Press. Every quarter-point rise in the Fed’s rate feeds through to mortgage rates, and every rise in mortgage rates locks more buyers out of the market. The Fed faces a genuine dilemma: inflation is still above target, but the medicine is already biting the real economy. Thursday’s yields suggest the market believes the Fed will choose to keep administering the medicine. The risk is that it administers too much, too late — the classic error that turns a slowdown into a recession.
5. Tuesday is the real test
Everything about Thursday’s session was, in a sense, provisional. The market does not yet know who will run Nvidia, what Ms Kress will say about the outlook, or whether the demand for AI chips is as strong as the analysts’ forecasts assume. It does not know whether Mr Trump’s dismissal of a deal with Iran is a negotiating tactic or a statement of intent. And it does not know whether the Fed will raise rates by 25 or 50 basis points in December, or how many more rises will follow.
Some of those questions will be answered on Tuesday, when Nvidia reports its October-quarter results. A 92 per cent revenue surge and a $60 billion profit would be extraordinary for any company; for a company that has just lost its founder-chief executive to scandal, they would be a statement that the business is bigger than the man. A miss, or a cautious outlook from Ms Kress, would confirm the market’s worst fear: that the AI boom was always more fragile than it looked, and that its most important company was held together by one person’s will. Thursday’s partial recovery bought the market five days. Tuesday will decide whether the money was well spent.
What to Watch Next
- Nvidia’s earnings on Tuesday 17 November: revenue, profit and, above all, Ms Kress’s outlook for the current quarter — and any word on the succession search.
- The succession race: whether Ian Buck, Ms Kress or an outside candidate emerges as the permanent chief executive, and how quickly the board moves.
- US producer price inflation on Friday: the October PPI report will show whether the price pressures in Tuesday’s CPI data are spreading through the supply chain.
- The International Energy Agency’s monthly oil report on Friday: its assessment of supply, demand and the impact of the Hormuz attacks on global flows.
- Brent crude around $100: whether the rally extends towards OCBC’s year-end forecast, and whether further tanker incidents or presidential posts drive it higher.
- The Federal Reserve’s December meeting on 8–9 December: whether the rise is 25 or 50 basis points, and what officials signal about the path into 2027.
- The 10-year Treasury yield above 5 per cent: whether it holds, and what it means for mortgage rates, corporate borrowing and the housing market’s 16-year low in sales.
Sources
- Associated Press — Wall Street shakes with swings for Nvidia and oil prices but recovers most of its early losses
- Reuters — Nvidia PE falls to 14-year low, but CEO exit and AI worries cloud the bargain
- Reuters — Wall Street withstands AI blues. What about Nvidia shock?
- Wall Street Journal — Oil Prices Rebound as Trump Questions Need for Iran Deal
- Bloomberg via Rigzone — Oil Rises as Trump Dims Iran Deal Hopes
- Reuters via KWSN — Fed’s Hammack signals support for gradual rate-hike path

About the Author — Abdul Mannan
Related Articles
Jensen Huang Resigns as Nvidia Chief Executive After 33 Years as Affair Scandal Engulfs the AI Giant
Jensen Huang has resigned as Nvidia's chief executive after 33 years, with finance chief Colette Kress named interim…
Japan’s Wholesale Inflation Jumps to 7.1% as Weak Yen and Costly Oil Keep a December Bank of Japan Rate Hike in Play
Japan's wholesale prices rose 7.1% in October, beating forecasts and strengthening the case for the Bank of Japan…
Nvidia Board Prepares to Oust Jensen Huang After Second Affair Report as Shares Plunge
Nvidia's board is preparing to remove Jensen Huang as chief executive after reports of a second extramarital affair,…