
Japan’s Wholesale Inflation Jumps to 7.1% as Weak Yen and Costly Oil Keep a December Bank of Japan Rate Hike in Play

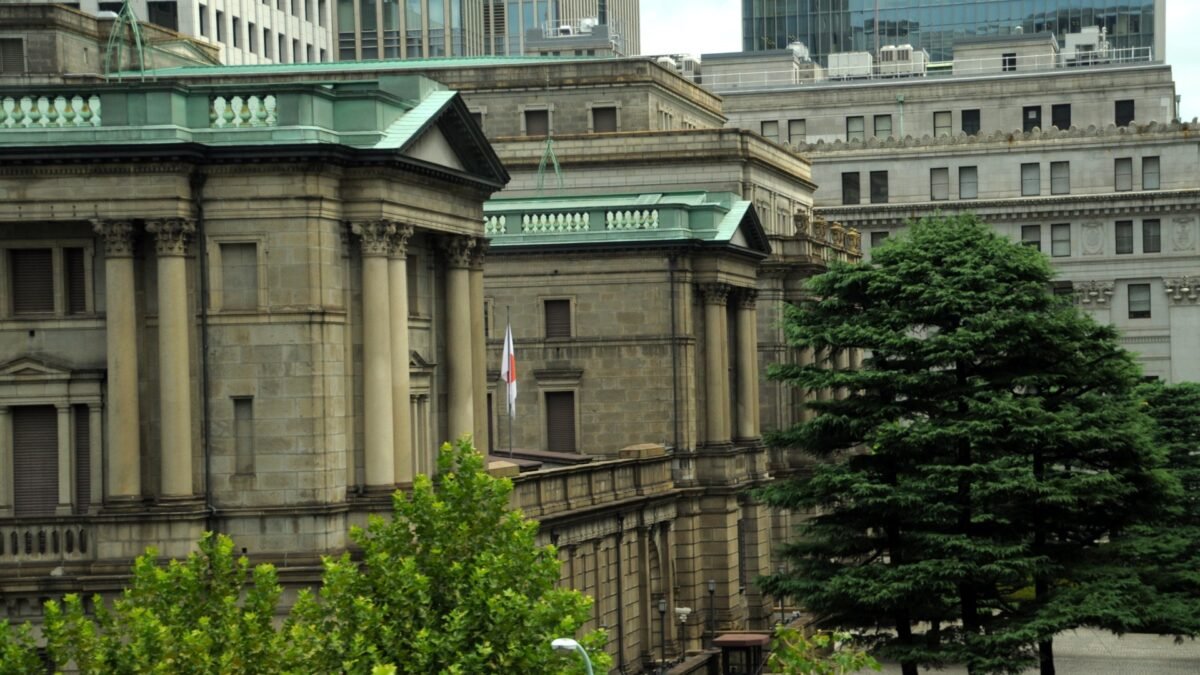
Japan’s wholesale inflation accelerated in October, rising faster than economists had expected and strengthening the case for the Bank of Japan to raise interest rates at its final meeting of the year, according to data released by the central bank on Thursday.
The corporate goods price index, which measures the prices companies charge each other for goods and services, rose 7.1% in the year to October, the Bank of Japan said, faster than the 6.5% increase forecast in a median survey of economists and up from a 6.8% rise in September, according to Reuters. On a monthly basis, producer prices climbed 0.7%, the steepest gain in five months, reversing a downwardly revised 0.2% drop in September, according to Seeking Alpha.
The figures will be among the factors the Bank of Japan weighs at its next policy meeting on December 17 and 18, when many analysts expect it to raise its policy rate to 1.5% from 1.25%, according to Reuters. Pricing in overnight index swaps implies an 82% probability of an increase at that meeting, according to Bloomberg, while a Reuters poll in October found that 54 of 78 economists predicted a December rise.
A move in December would make 2026 the first year since 1989 in which the Bank of Japan has raised interest rates three times, underlining how far the world’s fourth-largest economy has travelled from the era of rock-bottom borrowing costs. The central bank has already increased its policy rate twice this year, in June and September, and held it at 1.25% at its October meeting in an 8-1 vote.
What the Data Showed
The October acceleration was broad, and it was driven by the two forces that have defined Japan’s inflation story for much of this year: expensive energy and a weak currency. Petroleum and coal goods prices rose 15.9% in the year to October, faster than an 11.5% gain in September, while prices of chemical goods were up 15.5% after a 13.4% increase in September, according to Reuters.
“A wide range of goods saw prices rise as firms continued to pass on rising labour and raw material costs,” Sayaka Yamazaki, head of the Bank of Japan’s price statistics division, told a news briefing, according to Reuters. She added that firms had timed price hikes for the October start of a new quarter and the second half of Japan’s fiscal year, which ends in March 2027.
October marks the start of the second half of Japan’s fiscal year, when many businesses tend to implement price changes, according to Bloomberg. That seasonal pattern helps explain why the monthly increase was the largest since May, but it does not explain the whole story. The underlying pressures were visible across the index: prices of transportation equipment, such as automobile parts, rose 3.2% in October, accelerating from a 2.9% gain in September, as brisk demand related to artificial intelligence boosted prices of semiconductor chips, according to Reuters.
The clearest sign of the currency’s role came from the import side. The yen-based import price index rose 24.8% in October from a year earlier, the data showed, a sign that the currency’s weakness continued to push up the cost of raw material imports, according to Reuters. Japan is heavily reliant on imports of oil, raw materials and food, according to Bloomberg, so a weak yen feeds directly into the prices its companies pay — and, eventually, into the prices its households pay.
Wholesale inflation has now stayed above 6% since May, and July’s 7.7% reading was the fastest since February 2023, according to Reuters data. The October figure confirms that the pressure has not faded with the summer; it has, if anything, gathered force again.
“Wholesale inflation is likely to accelerate due to lingering uncertainty over the Middle East conflict, with a wide range of goods seen coming under upward price pressure,” Masato Koike, senior economist at Sompo Institute Plus, told Reuters. “While the BOJ could opt to stand pat if markets remain volatile, our baseline projection is for the central bank to raise interest rates in December,” he said.
The Yen at 160 and the Dollar’s Surge
The inflation data landed with the yen already under strain. The Japanese currency traded around 159.62 per dollar on Thursday morning in Tokyo, according to Bloomberg, approaching the key threshold of 160 — a level that traders watch closely because it has a history of drawing official action. The dollar was last trading at 159.80 yen, according to the Wall Street Journal, while the dollar index briefly edged above 103 for the first time since April 2025.
The yen has weakened about 1% over the past month, adding to import costs, according to InvestingLive. That slide is part of a broader dollar rally: the greenback has strengthened this week since United States inflation data came in hotter than expected, fuelling expectations of tighter monetary policy from the Federal Reserve, according to the Wall Street Journal. The combination of a firmer dollar, higher United States yields and elevated oil prices creates a tough near-term backdrop for Asian currencies, Lloyd Chan, a senior analyst at MUFG, said in a note carried by the Wall Street Journal.
The contrast between the two central banks is stark. In Washington, Federal Reserve Governor Christopher Waller put a 50-basis-point interest rate hike on the table for December after consumer prices rose more than expected, and money markets now price in a 91% probability of a 25-basis-point rise and a 9% probability of a 50-basis-point move at the December meeting, according to the Wall Street Journal. In Tokyo, the Bank of Japan is moving in the same direction but from the opposite starting point: after decades of near-zero rates, it is tightening slowly, and each step is debated.
For Japan, the weak yen is a double-edged sword. It flatters the earnings of exporters, whose overseas profits are worth more in yen, and it has helped push the Nikkei to record territory. But it also raises the cost of everything Japan must buy from abroad — above all energy — and that is exactly what Thursday’s wholesale figures captured. The yen-based import price index rising by nearly a quarter in a year is the arithmetic of that trade-off, and it is the reason the Bank of Japan cannot simply ignore the currency even though it does not target a particular exchange rate.
Markets Take It in Stride
Japanese stocks took the inflation surprise in their stride. The Nikkei 225 index climbed 0.4% to around 61,500 on Thursday, extending its winning streak to four sessions, according to Seeking Alpha, even as the yen traded near the psychologically important 160-per-dollar threshold.
The calm in Tokyo stood out against a weaker picture across much of Asia. Equities were broadly lower in Thursday trading, with South Korea’s Kospi dropping 0.6% and Taiwan’s Taiex falling 2.6%, according to the Wall Street Journal, while the Nikkei itself ended the session 0.4% higher. The drag came from the technology sector: shares in Nvidia tumbled more than 8% in after-hours trading after reports that its board was preparing to oust chief executive Jensen Huang, and futures tied to the Nasdaq fell 0.9% as the potential removal triggered a stress test of the already-fragile artificial intelligence trade, according to the Wall Street Journal.
Chinese artificial intelligence chip designers rose on Thursday, with MetaX and Cambricon Technologies rallying more than 8% each in Shanghai trading, while Shanghai Biren Technology gained more than 5% in Hong Kong, according to the Wall Street Journal — a sign that markets were separating Nvidia’s company-specific governance crisis from the broader artificial intelligence trade. That distinction mattered for Japan too: the same artificial intelligence demand that lifted semiconductor chip prices in the wholesale data is a genuine tailwind for Japanese suppliers, even as the Nvidia turmoil rattled the sector.
Oil prices fell on Thursday as traders weighed diplomatic efforts to end the conflict in the Middle East, according to the Wall Street Journal. Front-month Brent crude futures were 0.3% lower at $92.45 a barrel, and West Texas Intermediate futures fell 0.3% to $86.26 a barrel. Analysts at OCBC said oil’s geopolitical premium was fading amid diplomatic efforts and easing fears of fresh large-scale strikes, according to the Wall Street Journal, although the bank kept its end-2026 Brent forecast at $100 a barrel. The retreat in crude offers some relief, but it comes after oil surged above $100 a barrel last month, according to Bloomberg — the spike that fed directly into October’s wholesale prices.
The Road to December 17-18
The Bank of Japan’s December meeting is now the focal point for markets, and Thursday’s data sharpened the argument for a move. The central bank raised rates in September after delivering a hike in June — a shorter interval than the roughly twice-a-year hikes in 2024 and 2025, according to Reuters. At its subsequent meeting last month, the Bank of Japan kept policy steady but declared victory in its 14-year battle to hit its price target and flagged upside price risks, reinforcing its hawkish bias, according to Reuters.
That declaration matters. For more than a decade, the Bank of Japan’s overriding problem was deflation — prices that would not rise, however much money it printed. Its 2% inflation target, adopted in 2013, became a symbol of a goal that always seemed just out of reach. Last month the bank acknowledged that underlying inflation had hit its price target, according to Bloomberg, and a summary of opinions from its October meeting showed that some policymakers called for speeding up the pace of interest rate hikes as underlying inflation reached the central bank’s 2% target, according to Reuters.
The dissent at the October meeting pointed the same way. The bank held its policy rate at 1.25% in late October in an 8-1 vote, with board member Hajime Takata pushing for an immediate hike, according to InvestingLive. A Bloomberg survey published before that meeting showed 83% of economists expecting a December increase, according to InvestingLive — a consensus that Thursday’s data has only reinforced.
The case for December rests on three pillars. The first is the data itself: wholesale inflation is accelerating, not fading, and import costs are rising at nearly 25% a year. The second is the bank’s own language: having declared its price target reached and flagged upside risks, it would look inconsistent to sit on its hands if the numbers keep moving the wrong way. The third is the calendar: December is the last meeting of the year, and waiting until January would mean letting another quarter of price pressure pass without a response.
None of this makes a hike certain. The Bank of Japan has made a habit of surprising markets by moving more slowly than expected, and it has repeatedly stressed that it will act only when it is confident that inflation is durable rather than imported and temporary. But the balance of evidence has shifted. Where the question in the summer was whether the bank would tighten at all this year, the question now is whether it can afford not to.
The Case for Caution
Not everyone inside the Bank of Japan is convinced. Board member Toichiro Asada called on Thursday for careful timing on future interest rate hikes, cautioning that monetary tightening is increasingly weighing on economic activity as rates approach neutral levels, according to Seeking Alpha.
Speaking on Thursday, Asada noted that private consumption remains sluggish and recent price gains lack strong demand-side backing, warning that premature tightening could dampen growth and undercut underlying inflation, according to Seeking Alpha. His argument goes to the heart of the dilemma: the inflation Japan is experiencing is being driven largely by costs — oil, raw materials, a weak currency — rather than by strong demand from households. Raising rates does little to make oil cheaper, and it risks squeezing the very consumers whose spending the economy needs.
The caution is not abstract. Japan’s households have been squeezed by rising prices for years, and wage growth, while improving, has struggled to keep pace. If the Bank of Japan tightens too aggressively, it could choke off the fragile recovery in consumption before the virtuous cycle of wages and prices it has sought for so long has properly taken hold. Asada’s warning is a reminder that the bank’s board is not unanimous, and that the December decision will be argued, not rubber-stamped.
Koike’s caveat points in the same direction: the bank could opt to stand pat if markets remain volatile, according to Reuters. The Nvidia turmoil, the war in the Middle East and the prospect of a larger-than-expected Federal Reserve hike all add uncertainty, and the Bank of Japan has historically preferred to move when the global picture is settled rather than when it is in flux.
Why Wholesale Prices Matter
Wholesale inflation rarely makes headlines the way consumer prices do, but it is one of the earliest signals of where the cost of living is heading. The corporate goods price index tracks what companies charge each other, so it can hint at where consumer inflation heads next if businesses keep passing costs along, according to Finimize. When wholesale prices rise by 7.1%, the question is not whether households will feel it, but when — and how much of it companies absorb in their margins and how much they pass on.
For Japan, the pass-through channel is particularly direct. The country imports almost all of its oil and gas, much of its food and a large share of its raw materials, so global commodity prices and the exchange rate feed into domestic costs with little delay. The Middle East conflict has kept pushing up prices for fuel, and artificial intelligence-related demand has kept pushing up prices for semiconductor chips, according to Reuters. Both forces showed up in October’s data, and both are largely outside the Bank of Japan’s control.
That is what makes the December decision so difficult. The central bank can raise rates to support the yen and cool demand, but it cannot drill for oil or end a war. Its tools are blunt, and the inflation it is fighting is substantially imported. The best it can do is to keep expectations anchored — to convince businesses and workers that prices will stabilise — and to avoid the kind of currency slide that turns imported inflation into a spiral.
The timing of the October data also matters. October is when many Japanese firms reset prices for the second half of the fiscal year, and the breadth of the increases — a wide range of goods, in Yamazaki’s words — suggests that cost pressures are no longer confined to energy. When price rises spread from fuel and chemicals into transport equipment and beyond, they become harder to dismiss as a temporary shock, and that is precisely the pattern the Bank of Japan has said it watches for.
Analysis: Why It Matters
1. Three hikes in a year would end an era
If the Bank of Japan raises rates in December, it will have tightened three times in a single calendar year for the first time since 1989. That date is not a coincidence: 1989 was the year Japan’s asset bubble reached its peak, and the tightening that followed helped to bring it down — and ushered in the decades of stagnation that followed. The comparison is not a prediction, and today’s Japan is a very different economy, but it captures the scale of what is happening. A central bank that spent a generation trying to create inflation is now trying to contain it, and the speed of that reversal is the story of the year in Japanese monetary policy.
The deeper point is that the Bank of Japan’s framework has changed. For years its question was whether inflation would ever arrive; now its question is whether the inflation that has arrived is the right kind. The bank wants price rises driven by wages and demand, not by oil and a weak yen. Thursday’s data, with its energy-led increases and its 24.8% jump in import costs, is a reminder that the inflation Japan has is still largely the wrong kind — and that the bank’s task is to manage it without killing the wage growth that would make it sustainable.
2. The yen is doing the Bank of Japan’s work — and its damage
The yen’s slide toward 160 is both a symptom and a cause. It is a symptom of the gap between Japanese and American interest rates: with the Federal Reserve now contemplating a 50-basis-point hike and the Bank of Japan moving in quarter-point steps, money flows toward the higher yield. And it is a cause of the very inflation the Bank of Japan is trying to tame, because every yen of depreciation raises the cost of imports.
This circularity is the central bank’s trap. Raising rates should, in theory, support the yen and ease import costs. But if the Federal Reserve raises rates faster, the gap widens again, and the yen falls further. The Bank of Japan is therefore not really setting policy for Japan alone; it is setting policy in the shadow of Washington, and its room for manoeuvre depends on what the Federal Reserve does next. That dependence is uncomfortable for a central bank that prizes its independence, but it is the reality of a world in which the dollar remains the anchor currency.
The 160 level adds a further complication. It is the threshold at which Japanese officials have historically grown nervous, and traders know it. If the yen breaks through it decisively, the finance ministry may face pressure to intervene in the currency market — a step it has taken before, and one that would put the Bank of Japan’s careful choreography under strain. A rate hike in December would be, among other things, a way of supporting the yen without spending reserves.
3. The world is tightening again — just not together
Japan is not the only country whose central bank is moving toward higher rates. The Federal Reserve is openly debating a larger hike in December after hot inflation data, and a 25-basis-point interest-rate hike by the Bank of England in December is currently priced with a 75% probability, according to the Wall Street Journal. The era of coordinated easing that followed the pandemic is over; what has replaced it is a messier pattern in which each central bank responds to its own inflation, at its own pace, for its own reasons.
That divergence matters because it is what moves currencies, and currencies are what move trade. A world in which America tightens while Japan tightens more slowly is a world in which the dollar strengthens and the yen weakens — and in which Japan’s import bill keeps rising. The October wholesale figures are, in that sense, a snapshot of a global monetary cycle that is pulling in different directions at once, and of the costs that fall on the countries caught in between.
There is also a lesson here for the idea that inflation was finished. For much of the past two years, markets treated the post-pandemic inflation surge as a closed chapter. The return of wholesale inflation in Japan, the hot American consumer price data and the stubborn strength of oil all suggest that the chapter is not quite closed — and that central banks may have more work to do than investors had assumed.
4. Artificial intelligence is now an inflation story too
One of the more striking details in Thursday’s data is the role of artificial intelligence. Prices of transportation equipment rose 3.2% in October, accelerating from 2.9% in September, as brisk demand related to artificial intelligence boosted prices of semiconductor chips, according to Reuters. The same technology boom that has driven stock markets to record highs is now showing up in the prices companies pay for the hardware that powers it.
This is a new kind of cost pressure, and it complicates the usual story. The artificial intelligence boom is generally treated as a growth story — new investment, new productivity, new profits. But it is also a demand shock for a narrow set of inputs: advanced chips, the equipment that makes them, the energy that runs them. When demand for those inputs outstrips supply, their prices rise, and those rises ripple through every industry that uses them. The wholesale data captures that ripple at its source.
The irony is sharp. The same week that Nvidia’s leadership crisis sent technology shares tumbling and reminded investors how fragile the artificial intelligence trade can be, Japan’s wholesale figures showed how deeply that trade is now embedded in the real economy. The boom is no longer just a stock market story; it is a price story, and central banks will have to reckon with it as one.
5. The decision is December’s, but the test is January’s
Whatever the Bank of Japan decides in December, the real test will come in the months that follow. A rate rise to 1.5% would be the third of the year, but it would still leave Japanese borrowing costs far below those in America or Britain, and it would do little on its own to bring oil prices down or to end the Middle East conflict. Its value would be as a signal: that the bank is serious about its price target, that it will not let the yen slide unchecked, and that it expects businesses to keep passing on costs in an orderly way rather than in a panic.
The risk is that the signal is misread. If markets take a December hike as the start of a rapid tightening cycle, the yen could strengthen sharply, exporters’ earnings could suffer and the Nikkei’s record run could stall. If they take it as a one-off, the yen could keep sliding and import costs could keep rising, forcing the bank back to the table sooner than it would like. Threading that needle — tightening enough to matter, but not so much that it frightens — is the art of central banking, and it is an art the Bank of Japan has had little recent practice in.
For Japanese households, the stakes are more immediate. Wholesale inflation eventually becomes consumer inflation, and consumer inflation becomes the price of food, fuel and transport. The Bank of Japan’s December decision will not change what families pay at the petrol station next week, but it will shape whether the price rises of 2026 turn out to be a passing shock or the start of something more durable. That is what the bank is really deciding, and it is why a seemingly technical release about the prices companies charge each other deserves the attention it received on Thursday.
What to Watch Next
- December 17-18: The Bank of Japan’s final policy meeting of the year, when the board will decide whether to raise the policy rate to 1.5% from 1.25%. Watch the vote split and the governor’s press conference for guidance on the pace of further moves.
- The yen at 160: Whether the currency breaks decisively through 160 to the dollar, and whether Japan’s finance ministry signals any willingness to intervene in the foreign exchange market.
- November wholesale data: The next corporate goods price index release, due in mid-December, will show whether October’s acceleration was the start of a trend or a one-off driven by the October price-reset season.
- Japan’s consumer inflation: The national consumer price index for October and November will show how much of the wholesale pressure is reaching households — the pass-through the Bank of Japan is watching most closely.
- The Federal Reserve’s December decision: Whether the Fed opts for a 25- or 50-basis-point hike on December 9, and how the dollar responds, will shape the yen and the Bank of Japan’s room for manoeuvre.
- Oil and the Middle East: Whether crude prices stabilise below $100 a barrel as diplomatic efforts continue, or whether renewed tension pushes them higher and feeds back into Japan’s import costs.
- Wage negotiations: Early signals from Japan’s annual spring wage talks will indicate whether pay rises are keeping pace with prices — the factor that will ultimately decide whether the Bank of Japan’s inflation is sustainable.
Sources
- Reuters, “Japan wholesale inflation accelerates, keeps alive rate hike view”, November 12, 2026
- Bloomberg, “Japan’s producer prices pick up, backing case for another BOJ rate hike”, November 12, 2026
- Seeking Alpha, “Japan’s producer inflation accelerates to 7.1% in October; BoJ urges caution on rate hikes”, November 12, 2026
- InvestingLive, “Japan wholesale inflation speeds up to 7.1%, beating forecasts and firming BoJ hike bets”, November 12, 2026
- The Wall Street Journal, “Nvidia’s Leadership Crisis Weighs on Asian Markets”, November 12, 2026
- Finimize, “Japan’s Wholesale Inflation Heated Up, Keeping BOJ Hawks Talking”, November 12, 2026

About the Author — Abdul Mannan
Related Articles
Nvidia Board Prepares to Oust Jensen Huang After Second Affair Report as Shares Plunge
Nvidia's board is preparing to remove Jensen Huang as chief executive after reports of a second extramarital affair,…
Global Stocks Roar Back as CoreWeave Revives the AI Trade and Europe Hits a Record High
Global stocks surged on Wednesday as CoreWeave's strong results revived the AI trade, Europe's STOXX 600 closed at…
Nvidia Loses $430 Billion in Two Days as $7.5 Billion China Chip Claim and a Resignation Call Deepen the Huang Crisis
Nvidia has lost about $430 billion in market value in two days as a report alleged Jensen Huang's…