
Nasdaq Wipes Out Its 2026 Gains as Friday Rout Drags S&P 500 and Dow Into Correction

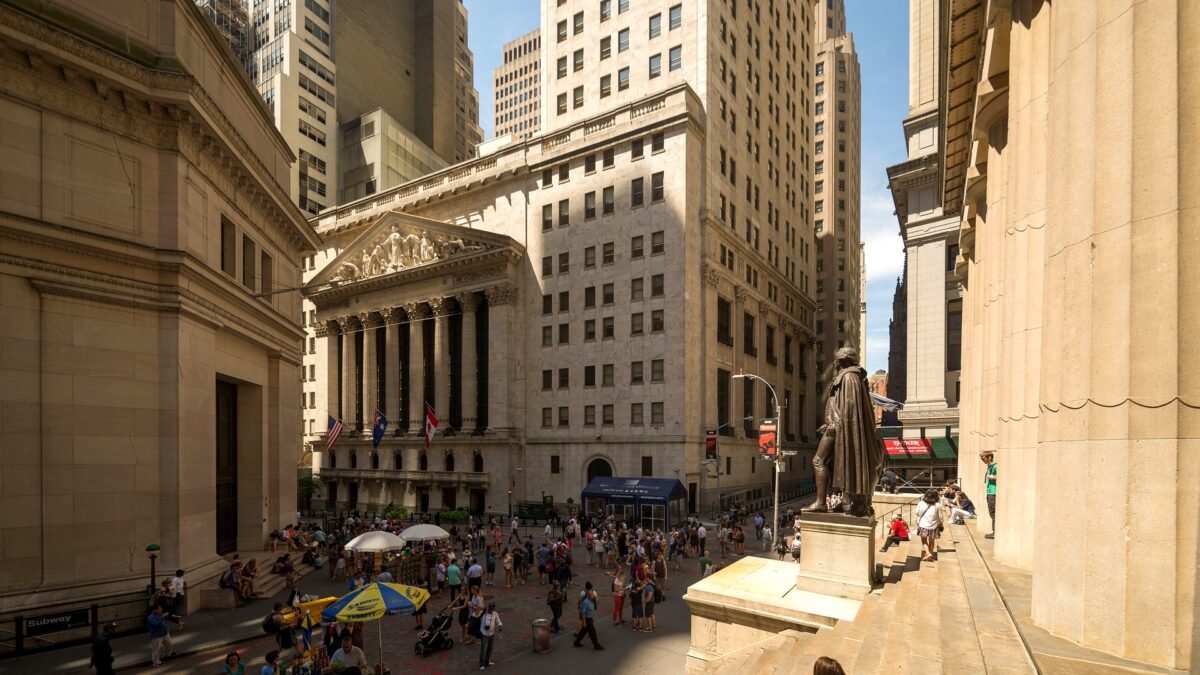
Wall Street suffered one of its worst days in years on Friday, 20 November, as a deepening sell-off in artificial intelligence stocks sent the Nasdaq Composite down 5.3 per cent, wiped out the technology-heavy index’s gains for the year and dragged the S&P 500 and the Dow Jones Industrial Average into correction territory.
The Nasdaq fell 1,261 points in a single session, the second-largest one-day points drop in its history, according to Investopedia, closing down nearly 3 per cent for 2026. The S&P 500 declined 3.7 per cent, its seventh consecutive daily loss, while the Dow fell 1.9 per cent, or more than 900 points. Both the S&P 500 and the Dow are now down more than 10 per cent from their recent highs, the standard definition of a correction.
It was the market’s worst week since the first week of April 2025, when President Donald Trump’s announcement of reciprocal tariffs sent stocks into a tailspin, according to Investopedia. The Dow finished the week down 8 per cent, the S&P 500 fell 8.6 per cent and the Nasdaq tumbled 10 per cent. For the Nasdaq, that weekly decline was the biggest since 2020, just surpassing the pullback that followed the Liberation Day tariff announcements in the spring of 2025, according to Reuters.
Just six weeks ago, the S&P 500 and the Nasdaq were trading at record-high levels. With Friday’s losses, the Nasdaq is down nearly 3 per cent for the year, while the other two major indexes are up less than 1 per cent, according to Investopedia.
Wall Street’s fear gauge, the Cboe Volatility Index, known as the VIX, soared 33 per cent to 37 on Friday, according to Reuters, its highest level since last year’s tariff turmoil. The yield on the 10-year US Treasury note fell 12 basis points to 4.93 per cent as investors sought the safety of government bonds.
Nvidia Leads the Rout After SEC Accounting Report
The heaviest selling was concentrated in the chipmakers and artificial intelligence stocks that had powered the market’s rally to record highs. Shares of Nvidia, the AI bellwether, fell 14 per cent on Friday and 23 per cent for the week, according to Reuters, after Reuters reported that the US Securities and Exchange Commission was examining the chipmaker’s accounting practices.
The SEC is probing Nvidia’s accounting, two people briefed on the matter told Reuters, adding to the legal troubles facing the scandal-hit chip giant. The Wall Street Journal reported on Tuesday that the SEC was probing Nvidia, but said it could not ascertain the focus of the investigation. The people who spoke to Reuters on condition of anonymity said SEC enforcement staff were scrutinising potential accounting issues at the company, although Reuters could not immediately determine when the SEC opened its inquiry or exactly what potential accounting issues the watchdog was examining.
Nvidia has lost one-third of its value in the past two weeks, according to Investopedia, as investors assess the impact of the departure of Jensen Huang from the chief executive post. Huang was ousted after revelations about his extramarital relationships, including with Alice Huang, whom US authorities suspect is a Chinese spy, according to Reuters. The Federal Bureau of Investigation and the SEC are investigating the former chief executive’s affair with the Chinese businesswoman, Reuters reported.
The crisis has sent shares in Nvidia, a linchpin of the AI boom, tumbling more than a third and stoked calls in Washington for tougher action on the technology threats posed by Beijing, according to Reuters. The company’s chief financial officer is serving as interim chief executive while also keeping the finance role, and its board has ruled out Huang’s return. The turmoil came despite Nvidia reporting a record quarter, with revenue of 115.8 billion dollars, a result that had been expected to steady the stock.
Other chip stocks fell sharply on Friday. Shares of Advanced Micro Devices dropped 13 per cent, while Broadcom, Marvell Technology and Micron each posted double-digit declines, according to Investopedia. The Philadelphia Semiconductor Index fell 11 per cent in a broad retreat from risk, according to Reuters, and the iShares Semiconductor exchange-traded fund lost 11 per cent.
Memory device makers, which had been among the biggest beneficiaries of the excitement surrounding artificial intelligence, were also among the largest decliners. Shares of SanDisk fell 16 per cent, while Seagate and Western Digital both dropped 12 per cent, according to Investopedia. Shares of Nvidia-backed companies Coherent and Nebius plunged 13 per cent and 16 per cent respectively.
Anthropic Slides in Its Second Session
Not even the blockbuster success this week of Anthropic’s initial public offering was enough to revive a market battered by fears that an AI bubble could burst. Anthropic shares fell nearly 9 per cent on Friday to around 89 dollars, according to Investopedia, after earlier falling as much as 14 per cent, according to Reuters.
The stock debuted on Thursday at 111.50 dollars, a big jump from the IPO price of 83 dollars, but closed the session at around 97 dollars, up 17 per cent on its first day. The IPO, which priced at 81.3 billion dollars and valued the Claude maker at 1.5 trillion dollars, was the biggest on record and immediately catapulted the AI lab into the ranks of the world’s largest companies by market capitalisation.
The IPO was expected to be a major test for the AI trade, but investors took little comfort from its success, according to Investopedia. The offering had drawn seven times more orders than shares on offer, yet the market’s verdict on its second day was that even the most celebrated AI company could not escape the wider retreat.
The selling spread well beyond chips and AI. Shares of SpaceX, which carried out its own massive IPO in June, fell 8 per cent on Friday. Among other mega-cap stocks, Meta Platforms declined 6 per cent and Tesla fell 8 per cent, while Amazon, Apple and Microsoft were also down sharply, according to Investopedia.
A Global Rout, From Tokyo to Frankfurt
The sell-off was not confined to the United States. Nearly 9 trillion dollars has been wiped off the value of world stocks since they peaked back in August, according to Reuters, and this week’s 17 per cent plunge in Taiwan is the biggest since the early 1990s.
In Europe, the German DAX fell 2.6 per cent on Friday and 7.29 per cent for the week, while the French CAC 40 dropped 1.89 per cent on Friday. The UK’s FTSE 100 fell 0.66 per cent on Friday and was on track for its sharpest weekly decline in eight months, according to Reuters, pressured by bank and energy shares as a weak global risk backdrop offset stronger-than-expected UK retail sales. The mid-cap FTSE 250 dropped 1.7 per cent and was set for a seventh straight day of declines, its longest losing streak since an eight-session slide in November 2025.
In Asia on Friday, the Nikkei 225 index in Tokyo ended down 5.1 per cent. In China, the Shanghai Composite closed down 1.2 per cent, while the Hang Seng index in Hong Kong fell 1.9 per cent. The S&P/ASX 200 in Sydney closed down 1.6 per cent. The falls in Asia had followed Thursday’s Wall Street sell-off, which had already spread across the region before the US market opened again on Friday.
Copper, a beneficiary of the AI rollout given high demand for the metal from data centres, is on course for its steepest weekly drop since April 2025, according to Reuters. Gold, however, is failing to play its safe-haven role, falling around 1 per cent on Friday to its lowest level since September 2025. Gold futures fell 4 per cent to 3,540 dollars an ounce, according to Investopedia, while bitcoin was at 59,000 dollars, trading at its lowest level since June, as investors steered clear of risky assets.
Oil went the other way. West Texas Intermediate crude futures rose 1.1 per cent to 84.10 dollars per barrel, according to Investopedia, as renewed US-Iran escalation risk kept traders focused on supply through the Strait of Hormuz. The Financial Times reported that Trump was weighing renewed strikes on Iran as the military warned of strain.
The dollar, meanwhile, has shown that reports of its demise have been greatly exaggerated, according to Reuters. The greenback index, which measures the world’s reserve currency against the six other top currencies, has risen to a 19-month high this week. The benchmark 10-year Treasury yield is on track for its biggest weekly fall since April 2025, down 17 basis points so far this week, according to Reuters.
Rates, the Fed and the AI Question
Two forces have combined to drive the rout, according to Reuters: worries over artificial intelligence and worries over US interest rates. Nerves about a possible bubble in AI and technology stocks started to emerge around the middle of the year, but the sell-off really started to snowball last month when it became clear that major economies such as the US would need further interest rate hikes to tame inflation.
The slide began in mid-October, and the pressure has intensified this week. The minutes of the Federal Reserve’s latest meeting, released this week, suggested the Fed was pretty unified about higher interest rates, according to LPL Financial’s Lawrence Gillum, speaking to Reuters. Fed governor Lisa Cook said monetary policy is not restrictive enough, and the University of Michigan’s consumer sentiment reading came in at 51.5.
“Interest rates are going up and we have signs of consumer inflation. The Fed is likely to raise rates at the December meeting and possibly the January meeting as well. Financial markets hate higher interest rates,” Tim Ghriskey, senior portfolio strategist at Ingalls & Snyder in New York, told Reuters. “Since mid-October when the slide began to happen there’s been more awareness of it. Fed speakers have been talking about it more. That’s the overriding issue.”
“The other issue is technology in general and AI. Some of that is valuation related and some is the disruption at Nvidia. It was the largest company in the US market and now it’s not,” Ghriskey added.
Gene Goldman, chief investment officer at Cetera, told Reuters: “This week’s chip earnings were an earnings test, and they passed it. Yesterday’s AI IPO is a valuation test, and with the 10-year around 5 per cent and the Fed still hiking, investors are asking how much of the AI story is already priced in.”
Richard Saperstein, chief investment officer at Treasury Partners, told Reuters: “The stock market is going through an AI repricing, reflecting an environment of slowing data centre buildouts, reduced funding sources for AI-related projects and a slower trajectory of technology-related earnings growth. This has been exacerbated by the Nvidia crisis and the Democratic midterm win, which were a one-two punch for the AI story.”
“Investors are broadly reducing exposure to technology and AI-related equities in favour of non-technology sectors, such as health care, energy and utilities,” Saperstein added. “Within technology, we still like the hyperscalers, which can benefit from any slowing data centre buildouts since they already own many of them, and cybersecurity, as the recent wave of cyber outages increases demand for their products.”
Even so, investors largely told Reuters they continued to believe in the AI trade, which took markets to record highs as recently as last month. Michael Monaghan, portfolio manager and partner at Founder ETFs in Dallas, Texas, told Reuters: “In the short run, sentiment drives prices. In the long run, fundamentals do. Right now the market is selling first and asking questions later. In our view, the fundamentals remain strong, and we expect prices to reflect them over time.”
A Week That Started With a Record IPO
The scale of the reversal is striking because the week began with celebration. Anthropic’s IPO on Thursday was the largest in history, and its shares briefly valued the company at 2 trillion dollars on its first day of trading. The offering was meant to be a vote of confidence in the AI industry, the biggest test yet of whether the market still believed in the technology’s promise.
Instead, the debut coincided with the market’s worst week in a year and a half. The contrast captures the tension at the heart of the sell-off: investors still believe in artificial intelligence as a technology, but they are no longer willing to pay any price for it, and they are no longer willing to look past rising interest rates, slowing data centre spending and the turmoil at the industry’s most important company.
The week also brought fresh evidence of how quickly the mood has changed. On Wednesday, the Dow dropped 849 points as the global sell-off deepened and the S&P 500 hit its lowest close since July. On Thursday, Wall Street’s sell-off spread to Asia, with the S&P 500 hitting a seven-month low and the Nikkei plunging 5 per cent. Friday’s session was worse still, with the Nasdaq suffering its second-largest one-day points drop ever.
President Donald Trump said on Friday that he had secured two new trade deals, with ten others coming very soon, according to a market wrap, but the announcement did little to slow the selling. The market’s focus was elsewhere: on the Federal Reserve, on Nvidia, and on the question of whether the AI boom that carried stocks to record highs has finally run ahead of itself.
Analysis: Why It Matters
1. A correction is a fact, not a forecast
The most important thing Friday established is definitional: the S&P 500 and the Dow are now in correction territory, down more than 10 per cent from their highs, and the Nasdaq has given back its entire gain for the year. That matters because corrections change behaviour. Pension funds rebalance, margin calls arrive, and the retail investors who bought every dip on the way up discover that dips can keep falling. The language of the market shifts from “when will it recover” to “how much further can it fall”, and that shift in psychology is itself a market force. Nothing about Friday’s numbers guarantees further declines, but the correction label is now attached to the two broadest measures of American wealth, and it will shape every conversation about the market from here on.
2. Nvidia is no longer just a stock
The most dangerous element of this sell-off is that its epicentre is a single company that had become the symbol of the entire AI boom. Nvidia was the largest company in the US market, the linchpin of the AI trade, and the stock that every pension fund, every index fund and every growth portfolio owned. Now it has lost a third of its value in two weeks, its chief executive has been ousted amid a scandal involving an alleged Chinese spy, the FBI and the SEC are investigating, and Reuters reports that the SEC is examining its accounting. That is not a normal earnings disappointment. It is a crisis of confidence in the company that embodied the boom, and it raises a question no investor can dodge: if the numbers at the heart of the AI story are under official scrutiny, what else in the story deserves a second look? The probe may find nothing. But the market is not waiting to find out.
3. The Anthropic test failed, and that is the point
Anthropic’s IPO was supposed to settle the argument. The biggest offering in history, seven times oversubscribed, a company valued at 1.5 trillion dollars on its first day: if that could not revive the market, the thinking went, nothing could. On Friday it fell 9 per cent. The failure matters precisely because the IPO itself was a triumph. It shows that the problem is not confidence in any single AI company, but confidence in the prices the market has put on all of them. When the most celebrated debut in history cannot hold its gains for 48 hours, the market is saying that the AI story is real but the valuations were not. That is a healthier verdict than a bubble bursting, but it is a verdict that still costs trillions.
4. Rates have replaced the AI story as the market’s master
For two years, artificial intelligence was the force that explained everything in the market: the rally, the concentration, the record highs. This week, interest rates took that role. The Fed’s minutes, the prospect of hikes in December and possibly January, and the 10-year yield’s surge earlier in the month have reframed every AI valuation. As Gene Goldman put it to Reuters, with the 10-year around 5 per cent and the Fed still hiking, investors are asking how much of the AI story is already priced in. The irony is that the AI spending boom itself is part of the reason rates are rising: the data centre buildout has been a tailwind for economic growth, and slower AI spending could, as Lawrence Gillum noted to Reuters, mean slower growth, lower inflation and a Fed that does not have to hike as aggressively. The market is caught between two fears, of too much AI spending and of too little, and Friday was the day it decided to fear both at once.
5. The global spread is the real warning
A sell-off confined to American technology stocks would be a sector story. This one is not. Nearly 9 trillion dollars has been wiped off world stocks since August, Taiwan has suffered its biggest weekly plunge since the early 1990s, European markets have fallen for a week, the dollar is at a 19-month high, copper is on course for its steepest weekly drop since April 2025, and even gold and bitcoin, the assets investors usually flee to or flee from in opposite directions, fell together. When everything falls at once, the market is not repricing a sector; it is repricing risk itself. That is the pattern of April 2025, and it is the pattern investors should watch most closely. The good news, if there is any, is that April’s rout resolved quickly, with retail investors buying the dip and indexes returning to record highs within months. The bad news is that this time the trigger is not a policy announcement that can be reversed, but a set of questions, about AI valuations, about Nvidia, about interest rates, that have no quick answer.
What to Watch Next
- The SEC’s Nvidia inquiry: whether the regulator confirms the probe, what accounting issues it is examining, and whether Nvidia responds publicly.
- Nvidia’s leadership: who is named permanent chief executive, and whether the interim chief executive, who is also chief financial officer, can steady the company.
- The Federal Reserve’s December meeting: whether the Fed raises rates as markets now expect, and what it signals about January.
- Anthropic’s shares: whether the stock stabilises above its 83-dollar IPO price or falls below it, which would be a powerful signal about AI valuations.
- The 10-year Treasury yield: whether it stays below 5 per cent or climbs back above it, which would renew pressure on growth stocks.
- Whether the selling spreads from technology into the broader market, or whether the rotation into health care, energy and utilities that Richard Saperstein described continues.
- Retail investors: whether they buy the dip as they did after April 2025, or whether the correction shakes their confidence, which would deepen the decline.
Sources
- Reuters — Nasdaq plunges 5% a day after Anthropic debut, but investors still believe in AI
- Reuters — Nvidia’s accounting is a focus of US SEC investigation, sources say
- Reuters — The snowballing selloff in global markets
- Investopedia — Markets News, Nov. 20, 2026: Major Stock Indexes Sink, Wipe Out 2026 Gains as AI Trade Melts Down

About the Author — Abdul Mannan
Related Articles
Barclays Circles Metro Bank as £1.2 Billion Takeover Interest Emerges a Week After Challenger Put Itself Up for Sale
Barclays is among the early suitors circling Metro Bank after the challenger lender put itself up for sale,…
Wall Street Sell-Off Spreads to Asia as S&P 500 Hits Seven-Month Low and Nikkei Plunges 5%
Wall Street fell about 2% on Thursday, with the S&P 500 and Nasdaq at seven-month lows, before the…
Anthropic Closes Record Nasdaq Debut at $97.17, Up 17%, After Opening Pop Briefly Valued It at $2 Trillion
Anthropic closed its first day on the Nasdaq at $97.17, up 17% on its $83 IPO price, after…