Oil Eases From Six-Month High as Markets Brace for a Pivotal Week of Central Bank Decisions

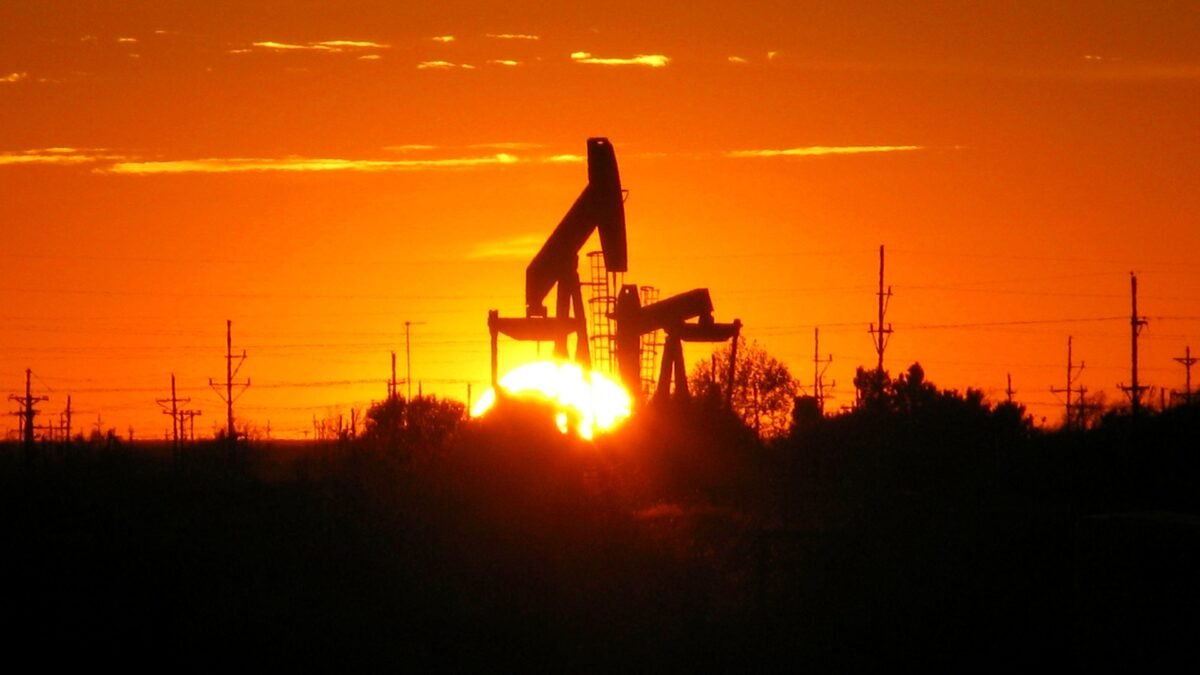
Oil pulls back after a turbulent week
Oil prices eased on Monday after surging to a six-month high last week, giving global markets a brief pause before a week packed with central bank decisions and some of the most important corporate earnings of the year. According to Reuters, Brent crude slipped about 1 per cent to $115.48 a barrel in early trading, while United States crude fell 1.1 per cent to $102.08 a barrel.
The pullback followed a violent move higher. According to Reuters, Brent futures jumped 6.2 per cent last week to their highest weekly close since mid-2022, as attacks by Houthi forces in Saudi Arabia stoked concern about energy supplies. Prices settled nearly $3 higher on Friday alone, according to Reuters, after a week in which supply fears, geopolitical tension and inflation worries combined to unsettle investors.
Monday’s easing was linked in part to diplomacy. According to Reuters, Qatari mediators were in Tehran on Sunday as part of an effort to de-escalate regional tensions in coordination with the United States. That report gave traders a reason to take some profit after the sharp run-up, even though the underlying risks had not disappeared.
The weekend brought no clean resolution. According to Reuters, the Houthis said they had attacked a Saudi airport and oil facilities on Saturday, while Saudi Arabia said on Sunday that it had intercepted more missiles and drones. According to Reuters, the kingdom’s main airport restarted partial operations on Sunday after damage in an earlier round of attacks, even as the militant group vowed to keep targeting the facility. For oil traders, that combination — a diplomatic opening on one side and continued attacks on the other — explains why prices fell only modestly rather than reversing the whole weekly gain.
Wall Street ended last week lower
The oil surge had already left its mark on equities before the weekend. According to market reports summarising Friday’s session, the Dow Jones Industrial Average fell 1.2 per cent to 52,215.16, the S&P 500 declined 0.5 per cent to 7,623.68, and the Nasdaq Composite shed 0.2 per cent to close at 25,955.34. The selling broadened beyond technology shares, a shift that mattered because much of the earlier market anxiety had been concentrated in artificial intelligence stocks.
According to market summaries, most members of the S&P 500 fell on Friday even as selling in technology eased. The Philadelphia Semiconductor Index edged higher on the day, according to those summaries, but still recorded its longest weekly decline since November. Energy was the exception: higher crude prices lifted energy shares to a record high on Friday, according to market reports, even as the broader market fell.
Over the full week, the picture was mixed rather than uniformly bleak. According to market summaries, the Dow gained 0.4 per cent for the week, while the S&P 500 fell 0.5 per cent and the Nasdaq lost 0.7 per cent. That split underlines an important point for readers: Friday’s sharp fall did not erase the whole week for every index, but it did change the mood heading into a decisive week for monetary policy.
Bond markets told a similar story of caution. According to Reuters, yields on United States 10-year notes were last down to 4.974 per cent, while yields on 30-year notes stood at 5.299 per cent, hovering near one-month lows after a recent safe-haven rally. Other market summaries put the 10-year yield at 4.99 per cent after Friday’s session, when Treasuries gave back part of Thursday’s rally. The small differences reflect different times of measurement, but the direction is consistent: elevated oil prices kept inflation worries alive, and that limited how far bond yields could fall.
A cautious start in Asia and Europe
Asian markets began Monday cautiously. According to Reuters, Japan’s Nikkei dipped 0.8 per cent after losing 4.0 per cent last week, while South Korea fell 0.4 per cent, having shed almost 19 per cent so far this month. According to Reuters, MSCI’s broadest index of Asia-Pacific shares outside Japan eased 0.1 per cent. Australian shares were set to open lower, according to market reports, with ASX 200 futures down 43 points, or 0.5 per cent, to 8,774.
Currency markets were subdued. According to Reuters, major currencies traded in tight ranges on Monday, with the dollar index — which measures the United States currency against a basket of peers — a shade weaker at 101.64. According to Reuters, the euro rose 0.16 per cent to $1.122, aided by relief that France was spared a Moody’s downgrade despite social unrest, while sterling strengthened 0.1 per cent to $1.3385. According to Reuters, the Japanese yen was largely steady at 156.920 per dollar, and the Australian dollar fetched $0.7030.
Europe had already felt the pressure on Friday. According to market reports, the Stoxx 600 fell 0.3 per cent for a second straight session and the FTSE 100 lost 0.3 per cent to 10,690.36. According to those reports, Kering dropped 17 per cent, its biggest fall on record, after its Gucci unit reported persistent weakness in China and a slowdown in North America. According to the same reports, Richemont fell 6.4 per cent, while L’Oréal rose 5.6 per cent to a two-year high on demand for hair care and premium skincare. The contrast between luxury names shows that investors were not simply selling everything: they were punishing companies exposed to weak Chinese demand while rewarding those with stronger product momentum.
Company news added to the sense of a changing corporate mood. According to market reports, American Express is cutting 5 per cent of its global headcount to contain costs, while Apple sold out of its limited in-store inventory of the iPhone Duo foldable, priced from nearly $2,000. According to those reports, SLB reported a gradual recovery in its Middle East business. None of these items alone moves a whole market, but together they sketch a corporate landscape in which cost discipline, premium pricing and energy exposure are all being tested at once.
The central bank week ahead
The main reason this week matters so much is the calendar. According to Reuters, the week packs in central bank meetings, with New Zealand’s central bank widely expected to raise rates on Wednesday. According to Reuters, markets assume the United States Federal Reserve will stand pat at its meeting this week, but imply an 80 per cent chance it will raise rates in December. According to Reuters, much the same is priced in for the Bank of Japan and the European Central Bank.
The Federal Reserve meets on October 27 and 28, with its decision due on Wednesday, October 28, according to previews of the meeting. According to those previews, futures markets put the odds of a hold in October at roughly 85 to 94 per cent, depending on the source and the day. The current federal funds target range is 3.75 to 4.00 per cent, according to those previews. What matters most, according to the same previews, is not the October decision itself — which is widely expected to be a hold — but what Fed Chair Kevin Warsh signals about December.
That December question is where oil enters the central bank debate. According to Reuters, the inflationary pulse from oil is likely to alarm all the central banks meeting this week, with rate rises seen as just a matter of time even if some hold for now. According to Reuters, JPMorgan’s global head of economics, Bruce Kasman, has assessed that the main message from global central banks grappling with this year’s macroeconomic surprises is that a relatively shallow rate-hike cycle is under way. According to Reuters, that assessment points to the major central banks remaining on hold for now, with Canada expected to start its tightening cycle and first moves expected from the United Kingdom and Sweden next month.
Two United States data releases will frame the Fed’s discussion. According to Reuters, a key reading on United States core inflation should show cost pressures remained elevated at 3.1 per cent in September, while the economy is forecast to have grown at a brisk 3.2 per cent annualised pace thanks in part to furious spending on data centres. If both forecasts prove broadly right, the Fed will face the classic dilemma in sharper form: growth strong enough to tolerate higher rates, and inflation sticky enough to demand them.
Consumer sentiment adds a warning from households. According to market reports, the University of Michigan’s final reading for October rose 1.4 points to 48.0 from the preliminary reading, but that level was still a five-month low. According to those reports, affordability constraints — including elevated inflation, high energy costs and high mortgage rates — were at the centre of the decline. According to the same reports, one-year inflation expectations picked up to 4.7 per cent and five-to-ten-year expectations rose to 3.5 per cent. Households, in other words, are not just reacting to today’s petrol price: they are expecting prices to stay higher for longer.
Analysis: Why It Matters
Three channels connect a barrel of oil to a household budget, a company balance sheet and a central bank decision — and all three were visible last week.
The first channel is direct and immediate. When crude rises, petrol, diesel, heating and transport costs tend to follow, even if the pass-through is not instant or complete. For airlines, hauliers and manufacturers, fuel is a large and hard-to-avoid cost. When those costs rise quickly, companies must choose between absorbing them, which squeezes margins, or passing them on, which feeds the very inflation central banks are trying to contain. Last week’s market action suggests investors were pricing in the second outcome: energy shares rose, while consumer and financial shares, which are more sensitive to spending and borrowing costs, dragged the indexes lower.
The second channel runs through bond yields and inflation expectations. Higher oil prices do not automatically mean higher overall inflation, but they do raise the risk that inflation expectations become unanchored — that workers, firms and shoppers start behaving as if higher prices are permanent. That is why a 10-year yield near 5 per cent matters so much. When long-term borrowing costs stay high, mortgages, business loans and government debt all become more expensive. A central bank that cuts rates into an oil shock risks looking as if it is ignoring that signal; a central bank that hikes into weakening consumer sentiment risks deepening the slowdown. The Fed’s likely October hold, combined with a high priced-in chance of a December hike, is best understood as an attempt to buy time while keeping both options credible.
The third channel is confidence. The Michigan sentiment data, weak even after a small upward revision, shows that households are already feeling the squeeze from energy and housing costs. Consumer spending has held up in headline growth figures, helped by data-centre investment and other business spending, but sentiment and spending are not the same thing. If households retrench while businesses keep investing heavily in artificial intelligence infrastructure, growth can look strong on paper while feeling fragile in daily life. That gap is politically and economically important, and it is one reason markets are watching earnings so closely this week.
Earnings provide the other half of this week’s test. According to market reports, Microsoft, Alphabet and Amazon are due to report, and Asia is entering its busiest reporting period, with about 550 of the roughly 1,200 companies in the MSCI Asia Pacific Index set to publish results, according to Bloomberg data cited in market reports. SK Hynix and Samsung Electronics, both major players in the artificial intelligence boom, are among them, according to those reports. After a chip sell-off that pushed the regional benchmark down more than 6 per cent this month, according to market reports, investors are asking a blunt question: do profits justify the enormous sums being poured into data centres, chips and power?
The SpaceX financing story illustrates the scale of that question, even though it is not this week’s news. According to Reuters reports from early October, SpaceX was seeking about $40 billion in financing to buy Nvidia chips, in a package of roughly $10 billion in bank loans and $30 billion in investment-grade debt. According to those reports, Morgan Stanley estimated that artificial intelligence infrastructure would require $1.5 trillion in external financing by 2028. Whether or not any single deal closes, the direction is clear: the artificial intelligence build-out is now a credit-market story as much as a technology story, and that makes lenders’ caution — and central banks’ rate path — central to its future.
For the Middle East, the stakes are different but equally sharp. Oil at $115 a barrel benefits producers in the short term, but a prolonged supply shock also invites demand destruction, diplomatic pressure and retaliation risks that no producer can fully control. The Qatari mediation effort reported by Reuters matters precisely because it offers a route back from escalation without any side having to concede publicly that it has changed course. Markets gave that effort some credit on Monday, but only some: a 1 per cent fall after a 6 per cent weekly rise is a pause, not a verdict.
For ordinary readers, the practical implication is not to overreact to a single day’s oil price. A one-day dip does not lower petrol prices overnight, and a one-week spike does not by itself cause a recession. What matters is persistence. If Brent stays above $110 for weeks, inflation forecasts, wage negotiations and central bank guidance will all shift. If it falls back below that level on genuine de-escalation, the pressure eases and the December hike pricing may soften. The next few days — the Fed decision, the inflation print, the technology earnings and the next headline from the Gulf — will tell us which path markets are actually on.
What to Watch Next
First, watch the Federal Reserve on Wednesday, October 28, and Chair Kevin Warsh’s press conference afterwards. The decision is expected to be a hold; the language about December, oil and inflation will move markets more than the decision itself. Second, watch the United States core inflation reading and the growth estimate: a hotter inflation print alongside strong growth strengthens the case for December action, while softer numbers give the Fed room to wait.
Third, watch technology earnings from Microsoft, Alphabet and Amazon, and the Asian reporting season. If earnings show that artificial intelligence spending is converting into revenue and cash flow, the recent chip sell-off may prove to be a correction within a boom. If they show rising costs without matching returns, the sell-off could broaden again. Fourth, watch the European Central Bank and the Bank of Japan later in the week, and New Zealand’s expected rate rise on Wednesday, for signs of whether the tightening bias is global or merely American.
Finally, watch oil itself — not just the price, but the news behind it. A confirmed de-escalation, a halt to attacks on Saudi facilities, or progress from Qatari mediation would support a further easing. A new attack, a threat to shipping or a breakdown in talks would likely send Brent back toward its recent highs and put Friday’s equity sell-off back in play. Until one of those paths becomes clear, expect volatility: markets are priced for a pivotal week, and pivotal weeks rarely pass quietly.
Sources
- Reuters — Currency markets subdued ahead of pivotal central bank week (26 October 2026)
- The Hindu BusinessLine (Reuters) — Crude oil price slips from six-month highs despite supply concerns (26 October 2026)
- Market Index — ASX 200 Live Today, Monday 26 October 2026
- Rivkin Report — Morning Market Wrap, 26 October 2026

About the Author — Abdul Mannan
Related Articles
Audi to Build $4 Billion Georgia Plant, Its First US Factory, as Trump Credits Tariffs
Audi will build its first US factory near Macon, Georgia — a roughly $4 billion plant building the…
Brent Crude Tops $116 as Wall Street Falls and the 10-Year Yield Returns to 5%
Brent crude settled at $116.72 a barrel on Friday as supply fears rattled Wall Street, pushing the Dow…
Volvo Cars Cuts 2,500 Jobs After Q3 Loss as China Sales Collapse and US Tariffs Bite
Volvo Cars will cut about 2,500 jobs, most of them in Sweden, after a third-quarter loss far larger…