
Walmart Beats Forecasts as Revenue Hits $188.8 Billion and Raises Full-Year Outlook — But Shares Slip

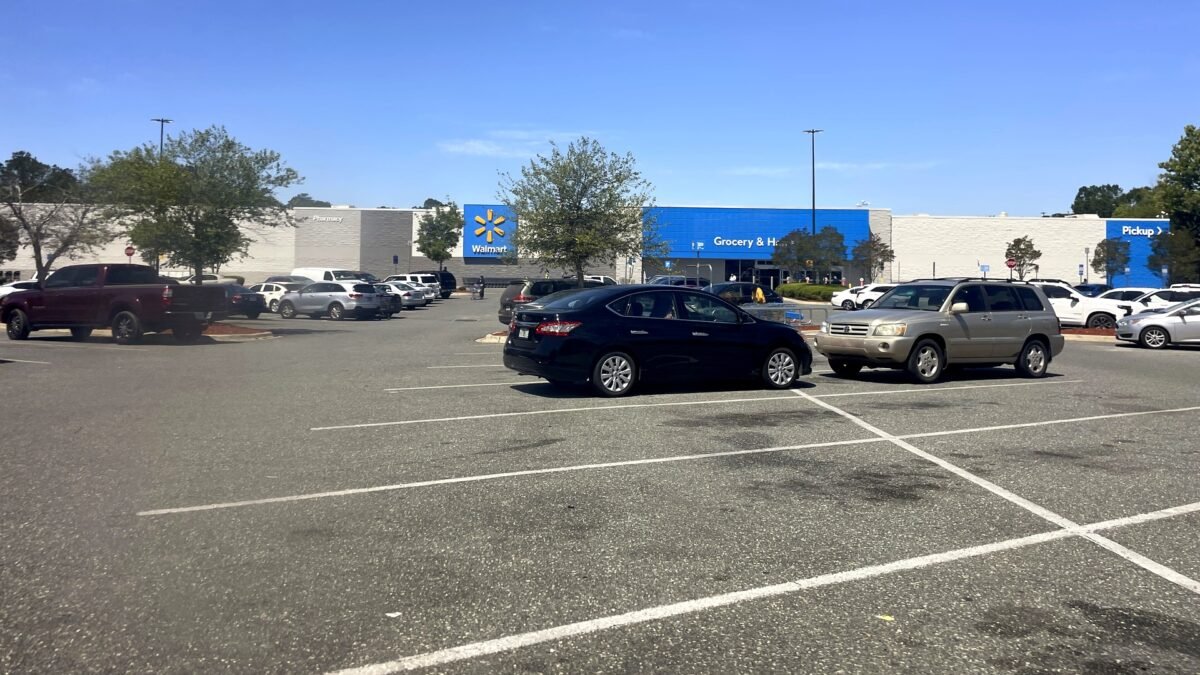
Walmart beat Wall Street’s forecasts for its fiscal third quarter on Thursday, reporting revenue of $188.8 billion and raising its full-year outlook for the second time this year, as American shoppers kept spending on groceries, general merchandise and online orders even while the wider stock market slid on fears of higher interest rates. The world’s largest retailer said the momentum would carry into the holiday season, but its shares slipped in premarket trading, a reminder that a good quarter is no longer enough when a stock has already climbed sharply into the results.
The Bentonville, Arkansas, company reported adjusted earnings of 65 cents a share for the three months ended 31 October, up from 62 cents a year earlier and ahead of the 64 cents analysts polled by FactSet had expected, according to Dow Jones Newswires. Revenue rose 5.2 per cent from a year earlier to $188.8 billion, topping the $187.4 billion analysts had been looking for. On a constant-currency basis, revenue grew 4.5 per cent, and enterprise net sales grew 4.4 per cent, comfortably above the top end of the guidance range of 3.0 to 3.75 per cent that Walmart gave in August.
Walmart also lifted its forecast for the full fiscal year, which ends in January 2027. It now expects adjusted earnings of $2.84 to $2.89 a share, up from the $2.80 to $2.87 range it set in August, and net sales growth of 4.9 to 5.2 per cent at constant currency, up from a previous range of 4 to 5 per cent. Wall Street had already pencilled in full-year profit of $2.89 a share, at the very top of the new range, which helps explain the muted reaction in the shares.
Operating income rose 16.0 per cent, or $1.1 billion, in the quarter, while adjusted operating income grew 5.5 per cent in constant currency. The gross profit rate expanded by 28 basis points, led by Walmart US. Operating cash flow reached $29.4 billion over the trailing twelve months, with free cash flow of $6.8 billion. The company also issued $6.5 billion in long-term debt during the quarter, and global inventory rose 8.1 per cent as it stocked up for the holiday season.
The American engine kept running
The core United States business did most of the work. Comparable sales at Walmart US rose 2.9 per cent excluding fuel, picking up from 2.6 per cent in the second quarter, as sales grew across categories and the company took market share. Online sales at Walmart US climbed 23 per cent, including nearly 50 per cent growth in marketplace sales, while the Walmart Connect advertising business grew 36 per cent excluding the VIZIO and Vibe businesses. Global e-commerce sales grew 17 per cent.
The comparable-sales figure was, however, a touch below what analysts had expected. Analysts polled by FactSet had been looking for growth of around 3.1 per cent, according to Barron’s, and that small shortfall was one of the reasons the shares edged lower before the market opened. Sales were also partly held back by a net headwind of about 70 basis points to comparable sales in health and wellness, driven by deflation related to the Maximum Fair Price Regulation, the government programme that caps the price of certain prescription drugs.
Sam’s Club, Walmart’s warehouse-club chain, delivered the strongest comparable-sales growth in the group. Comparable sales rose 4.9 per cent excluding fuel, beating the 4.63 per cent analysts had expected, and e-commerce sales jumped 30 per cent, supported by continued growth in club-fulfilled pickup and delivery, which grew by triple digits for the second consecutive quarter. Membership fee revenue grew 2.2 per cent, reflecting steady growth in member numbers and in the more expensive Plus tier, partly offset by the allocation of fees from a bundled membership offering.
That bundle is one of the clearest signs of how Walmart is trying to tie its businesses together. The company has brought its two biggest membership programmes together for the first time in a new $120 annual bundle that combines Walmart+ and Sam’s Club Plus, giving customers delivery, streaming and fuel savings in a single subscription. Membership fee revenue across the whole company rose 17 per cent in the quarter.
Tariff refunds are funding price cuts
One of the most important numbers in the results was not a sales figure at all. Walmart said it now has about 7,700 price rollbacks across categories in the United States, funded in part by tariff refunds it received earlier in the year. The refunds, paid back by US Customs and Border Protection after the courts struck down parts of the administration’s tariff regime, have become a quiet windfall for the biggest importers, and Walmart is spending its share on holding prices down rather than banking it as profit.
That choice is visible in the profit figures. Walmart said that when the second and third quarters are looked at together, underlying operating income growth increased by double digits over the period, and finance chief John David Rainey told investors to consider the two quarters together when judging the underlying growth of the business. The company had flagged the same point in August, when it said it was reinvesting tariff refunds received in the second quarter into customer experience and price in the second half of the year.
The strategy matters because Walmart’s customers are famously price-sensitive, and the company has spent the year telling investors that it would absorb tariff costs where it could rather than pass them on in full. Holding prices down costs margin in the short term, but it is also the reason shoppers keep coming through the doors, and it is the reason the company has been able to take share from rivals even as the economy has slowed.
According to Reuters, chief executive John Furner told investors on the earnings call that upper- and middle-income households are driving growth in the United States, and that the retailer continues to benefit from higher-income families shopping more frequently at Walmart. Walmart also said on the call that inflation is now running in the low single digits, in the low-1 per cent range, a sign that the price pressures which dominated the last three years have eased sharply, even if they have not disappeared.
The new profit mix: advertising, marketplace and membership
Behind the headline numbers, the quarter showed how far Walmart’s business model has moved from the simple business of selling goods off shelves. The company’s marketplace and fulfilment services had another strong quarter, with net sales up 49 per cent, the third consecutive quarter with growth above 45 per cent. Its advertising business, Walmart Connect, grew 36 per cent excluding VIZIO and Vibe, and 25 per cent including them. Membership fee revenue grew 17 per cent globally.
These are the businesses Walmart wants investors to focus on, because they grow faster and carry far higher margins than the grocery aisles. A marketplace sale, where a third-party seller pays Walmart a fee to reach its customers, and an advertising sale, where a brand pays to appear in front of a shopper who is about to buy, are both far more profitable than selling a tin of beans. The company described the shift in its release as an evolving business mix, diversifying its revenue and profit sources while strengthening its omnichannel leadership.
Technology is part of the same story. Walmart said usage of Sparky, its artificial-intelligence shopping assistant, rose 129 per cent year on year in the United States, and it is investing in agentic commerce, the emerging business of AI agents that shop on a customer’s behalf. The company has launched Agent Profiles and the Walmart Agent Gateway, and is helping to set the standards for how AI agents interact with its platforms, with the stated goal of making shopping through AI assistants more accessible while keeping customers in control of their purchases.
International: China soars, India waits
Walmart International grew sales by 3.3 per cent in constant currency, a solid but unspectacular figure that hides a sharp split between its markets. Sales in China rose 28 per cent, and e-commerce in both Canada and China grew by more than 30 per cent, with Sam’s Club businesses in both countries continuing to attract members. But growth was held back by the timing of Flipkart’s Big Billion Days sale in India, which shifted from the third quarter into the fourth, dragging down the international total.
The international division’s e-commerce sales grew only 2 per cent overall, entirely because of the Flipkart timing effect, and the company was clear that the drag was temporary rather than structural. The Indian festival season, which now falls in the fourth quarter, is expected to lift the numbers in the current period.
There was a warning from Mexico, however. Walmart’s Mexican unit, Walmex, missed third-quarter profit estimates in late October, according to Reuters, as rising costs and investments ate into margins. Net profit fell 6 per cent to 11.03 billion pesos, below the 12.26 billion pesos analysts polled by LSEG had expected, while revenue also came in shy of forecasts. It was a reminder that the same pressures Walmart faces at home, higher wages, heavier investment in stores and technology, apply across its empire, and that not every part of the business is firing at once.
A beat that the market greeted with a shrug
Shares of Walmart fell 0.7 per cent in premarket trading on Thursday, according to Barron’s, even though the company beat on both revenue and earnings and raised its outlook. The reaction was not a verdict on the quarter so much as a verdict on the price. Walmart’s shares had closed at $126.19 on 12 November, up 14.79 per cent from their intraday low of $109.93 on 9 October, and only about 7 per cent below their 52-week high of $135.16. A stock that has already run hard into its results needs a spectacular number to go higher, and this was a solid number, not a spectacular one.
The market backdrop did not help. Wall Street had a rough Wednesday. The Dow Jones Industrial Average fell 561 points, or 1.1 per cent, to 50,198, its third straight daily decline, while the S&P 500 slipped 0.2 per cent for its fifth consecutive losing session. Oil fell about 4 per cent, gold dropped to its lowest level in 14 months, and Bitcoin slid below $63,000. The selling was driven by minutes from the Federal Reserve’s October meeting, which showed that nearly all officials viewed further rate rises as appropriate, and by a call from Federal Reserve Governor Christopher Waller for a 50-basis-point rise in December. Walmart reported into a market that was already in a cautious mood.
There was also a sense that the guidance raise, while real, was modest. The full-year adjusted earnings range moved up by four cents at the midpoint, and the top of the new range, $2.89, is exactly where Wall Street already expected the year to land. When the market has already priced in the good news, delivering it is not enough to move the shares. Investors wanted a clearer steer on the holiday season, and the company, like most retailers, was careful not to promise too much with the biggest shopping weeks of the year still ahead.
The consumer, read through the biggest till in America
Walmart’s results are watched far beyond its own shareholders because the company is the clearest single read on the American consumer. Its till receipts are, in effect, a real-time survey of how households are feeling. When Walmart says upper- and middle-income families are shopping with it more often, that is not just a company boast. It is evidence of a trade-down that has been running for three years, in which households that once shopped at more expensive stores have moved their weekly shop to the cheapest reliable option, and have stayed there even as inflation has eased.
The picture was reinforced the day before, when Target, Walmart’s closest big-box rival, also beat forecasts and raised its full-year outlook ahead of the holidays, reporting that shoppers were returning to its stores. Two big retailers beating expectations in the same week, after months of warnings about a cautious consumer, suggests that the American shopper is more resilient than the headlines have suggested, even if the spending is concentrated on value and groceries rather than on discretionary treats.
That resilience will be tested in the next six weeks. Black Friday falls on 27 November, and the holiday season is the period when American retailers make a disproportionate share of their annual profit. Walmart is going into it with inventories up 8.1 per cent, about 7,700 price rollbacks in place, and a Thanksgiving offering from Sam’s Club that underlines the value pitch: an 11-item Member’s Mark spread that feeds up to 16 people for less than $10 each. The message to shoppers is unmistakable, and it is the same message the company has been sending all year: come here, and your money will go further.
Analysis: Why It Matters
The beat was real, but the bar was higher
Walmart did everything a company is supposed to do in an earnings report. It beat the revenue forecast, beat the earnings forecast, raised the outlook, and showed growth in every part of the business that matters for the future. And the shares fell anyway. That is not a contradiction. It is how markets work when a stock has already risen by nearly 15 per cent in five weeks and the guidance raise lands exactly where the consensus already sits. The lesson for investors is that the question is never whether the numbers are good. It is whether they are better than the numbers the market has already imagined, and this time they were not, quite.
Tariff refunds have become a price war
The most consequential line in Walmart’s release may be the one about 7,700 rollbacks. The tariff refunds that followed the court rulings against parts of the administration’s tariff regime have handed the biggest importers billions of dollars, and Walmart is spending its share on cutting prices. That turns a legal windfall into a competitive weapon. A smaller rival that did not import as much, or that kept the refund as profit, cannot match 7,700 price cuts. The refunds were meant to compensate importers for tariffs they should never have paid. In Walmart’s hands they have become a way to widen the price gap with everyone else, and that gap is the company’s oldest and most durable advantage.
The consumer is trading down, not giving up
The detail that upper- and middle-income households are driving Walmart’s growth deserves more attention than it has received. For decades, Walmart’s core customer was the lower-income household. When richer shoppers start doing their weekly shop at Walmart, it means the trade-down that began during the inflation surge has become a habit rather than a temporary squeeze. Households that discovered Walmart when prices were rising have not gone back to their old stores now that inflation has eased to the low single digits. That is good news for Walmart and bad news for the mid-market retailers those shoppers left behind, and it explains why the company’s comparable sales have held up even as the wider economy has cooled.
Advertising and the marketplace are the future of the profit line
Grocery retailing is a low-margin business, and Walmart knows it. The reason the company can afford to cut prices on 7,700 items is that it is increasingly making its money elsewhere: from the brands that pay to advertise on its platforms, from the third-party sellers that pay to use its marketplace, and from the members who pay for Walmart+ and Sam’s Club Plus. These businesses grew by 17 to 49 per cent in the quarter, while the core retail business grew by about 5 per cent. The strategy is clear, and it is the same one Amazon has pursued for a decade: use the store, physical or digital, to attract the shopper, and make the profit from the services wrapped around the sale. The difference is that Walmart has a vast network of physical stores across the United States to anchor the model, and that physical footprint is something no pure online rival can copy quickly.
The holiday season is the real test
For all the detail in this report, the quarter that matters most is the one that has just begun. The fourth quarter, which includes Thanksgiving, Black Friday and Christmas, is when Walmart makes a disproportionate share of its profit, and it is when the company’s claims about value will be tested by shoppers with real money to spend. Inventories are up 8.1 per cent, the price rollbacks are in place, and the guidance has been raised. But the consumer is still cautious, the Federal Reserve is talking about raising rates rather than cutting them, and the stock market has just had its worst week in months. If shoppers spend freely in December, this report will look like the prelude to a strong finish. If they do not, the raised guidance will look optimistic. The next six weeks will tell us which it is.
What to Watch Next
- The holiday numbers: Black Friday on 27 November and the December trading period will show whether the value pitch is converting into festive spending, and whether the 8.1 per cent rise in inventory was justified.
- Fourth-quarter guidance: Walmart’s next update will show whether the raised full-year range was conservative or whether the company expects the holiday season to deliver more than the market currently assumes.
- Comparable sales: whether Walmart US can push comparable sales back above 3 per cent, the level analysts had expected this quarter, or whether the 2.9 per cent print marks a new, slower pace.
- Flipkart’s festival season: with Big Billion Days shifted into the fourth quarter, the international division should rebound sharply, and the size of that rebound will show how much of the third-quarter softness was timing and how much was real.
- The tariff-refund pipeline: whether more refunds flow through, and whether Walmart keeps spending them on price cuts or starts letting more of the benefit drop to the bottom line.
- Interest rates: the Federal Reserve’s December meeting, and whether Governor Waller’s call for a 50-basis-point rise gains support, will shape both consumer borrowing costs and the valuation investors are willing to pay for Walmart’s shares.
- The AI shopping race: whether Sparky and the company’s agentic-commerce tools, including Agent Profiles and the Walmart Agent Gateway, start to show up in sales figures, and how rivals, including Amazon and Target, respond.
Sources
- Walmart — Walmart Releases Q3 FY27 Earnings (official company release)
- Morningstar / Dow Jones Newswires — Walmart Raises Fiscal Year Guidance Amid 3Q Earnings Beat
- Barron’s — Walmart Stock Falls as Forecast Leaves Wall Street Asking for More
- QNC News — Walmart Beats Forecasts With 188.8 Billion Dollars in Quarterly Revenue and Raises Full Year Outlook
- Business Wire — Walmart Reports Revenue Growth of 5.2%, Up 4.5% in Constant Currency
- Seeking Alpha — Walmart Non-GAAP EPS of $0.65 Beats by $0.01, Revenue of $188.84B Beats by $1.59B

About the Author — Abdul Mannan
Related Articles
Fed Minutes Point to More Rate Rises as Waller Calls for a 50-Point December Hike
Minutes of the Federal Reserve's October meeting show almost all officials expect further rate rises, and Governor Christopher…
Nvidia Shares Fall for Fifth Straight Day Despite Record $115.8 Billion Quarter as SEC Probe and House Demands Pile On
Nvidia's shares fell for a fifth straight session despite a record $115.8 billion quarter, as a reported SEC…
Target Beats Forecasts as Shoppers Return, Raising Its Full-Year Outlook Ahead of the Holidays
Target earned $2.65 a share in its third quarter, beating forecasts as comparable sales rose 5.6% on a…